Home Blog Page 798

Approaching.ai Brings in Top Scientists to Capture AI’s Inference Boom


BEIJING, CHINA – Media OutReach Newswire – 25 March 2026 – Approaching.ai has announced the appointment of two leading figures in computer science to accelerate its growth in high-efficiency AI infrastructure. Academician Wei-Min Zheng has joined as Chief Scientific Advisor, and Professor Yongwei Wu has been appointed Chief Scientist.

This move strengthens the company’s technical leadership and reinforces its long-term competitive moat in AI inference and Token production.

World-Class Expertise Reinforcing Technical Moat

Academician Wei-Min Zheng is a globally recognized authority in high-performance computing, distributed systems, and AI. His work on scalable storage architectures and parallel systems has had significant academic and industrial impact, earning multiple national science and technology awards.

Professor Yongwei Wu, an IEEE Fellow and AAIA Fellow, is an internationally recognized expert in parallel and distributed systems, cloud storage, and big data infrastructure, with multiple prestigious awards.

Their addition significantly enhances Approaching.ai’s ability to drive system-level innovation in large-scale AI inference—an area increasingly viewed as the core value layer of the AI industry.

Capturing the Core Value Layer: Inference and Token Production

As large models scale globally, demand for AI Tokens is growing exponentially. Inference is rapidly becoming the primary cost center and a key determinant of commercial viability.

Approaching.ai focuses on high-efficiency AI Token production, improving Token output per unit of compute and reducing deployment costs for enterprises.

Through system-level innovation, the company addresses key industry challenges:

  1. Fragmented computing resources
  2. Low inference efficiency
  3. Lack of standardized infrastructure

Its technologies—such as heterogeneous computing coordination and memory-compute optimization—enable unified execution across diverse hardware and models, creating a scalable and cost-efficient inference layer.

Strong Origin and Execution Capability

Originating from Tsinghua University’s High-Performance Computing Institute, Approaching.ai brings over 20 years of expertise in computing and storage systems, along with proven capability in translating research into industrial deployment.

Capital Validation and Market Confidence

Approaching.ai has attracted strong backing from leading venture capital firms and strategic investors, including GL Ventures, Verity Ventures, Shanghai Guofang Innovation Private Equity Fund Partnership (Limited Partnership), Xinglian Capital, Shangshi Capital, Tsinghua Capital, and other industry partners.

This reflects strong market confidence in the company’s positioning within the rapidly growing AI infrastructure market, particularly in inference optimization.

Looking Ahead

With strengthened scientific leadership, Approaching.ai will continue advancing enterprise-grade inference solutions and scalable AI infrastructure.

By focusing on Token production, the company targets one of the highest-leverage segments in the AI value chain and is well positioned to benefit from continued growth in AI adoption.

Hashtag: #AI

The issuer is solely responsible for the content of this announcement.

DITP Hosts Thai Night Hong Kong 2026 to Strengthen Thailand’s Entertainment Industry Networks with Global Partners


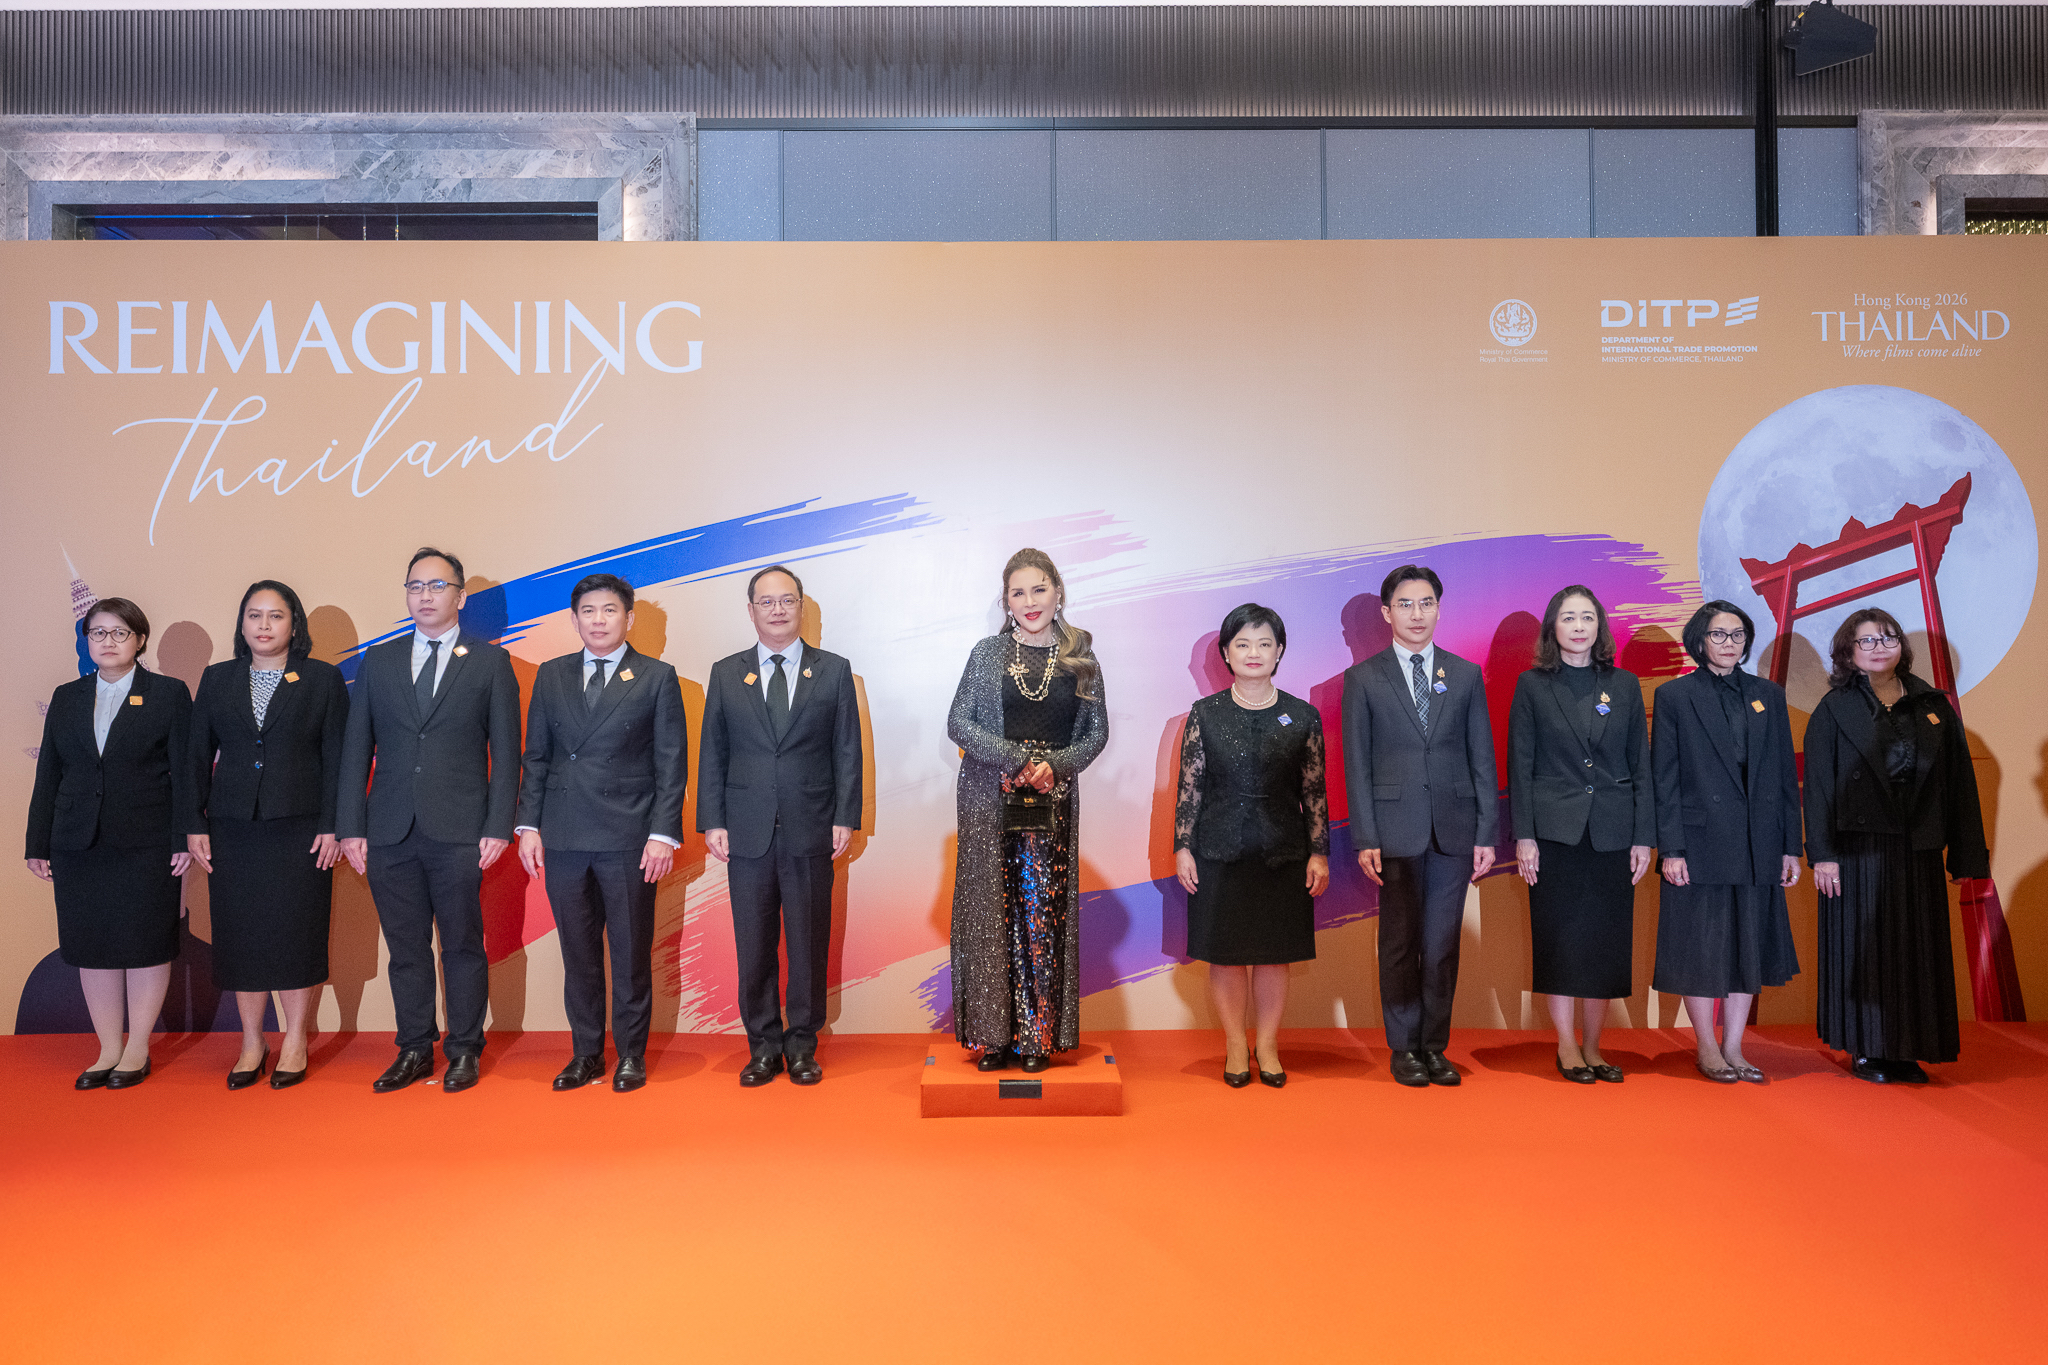
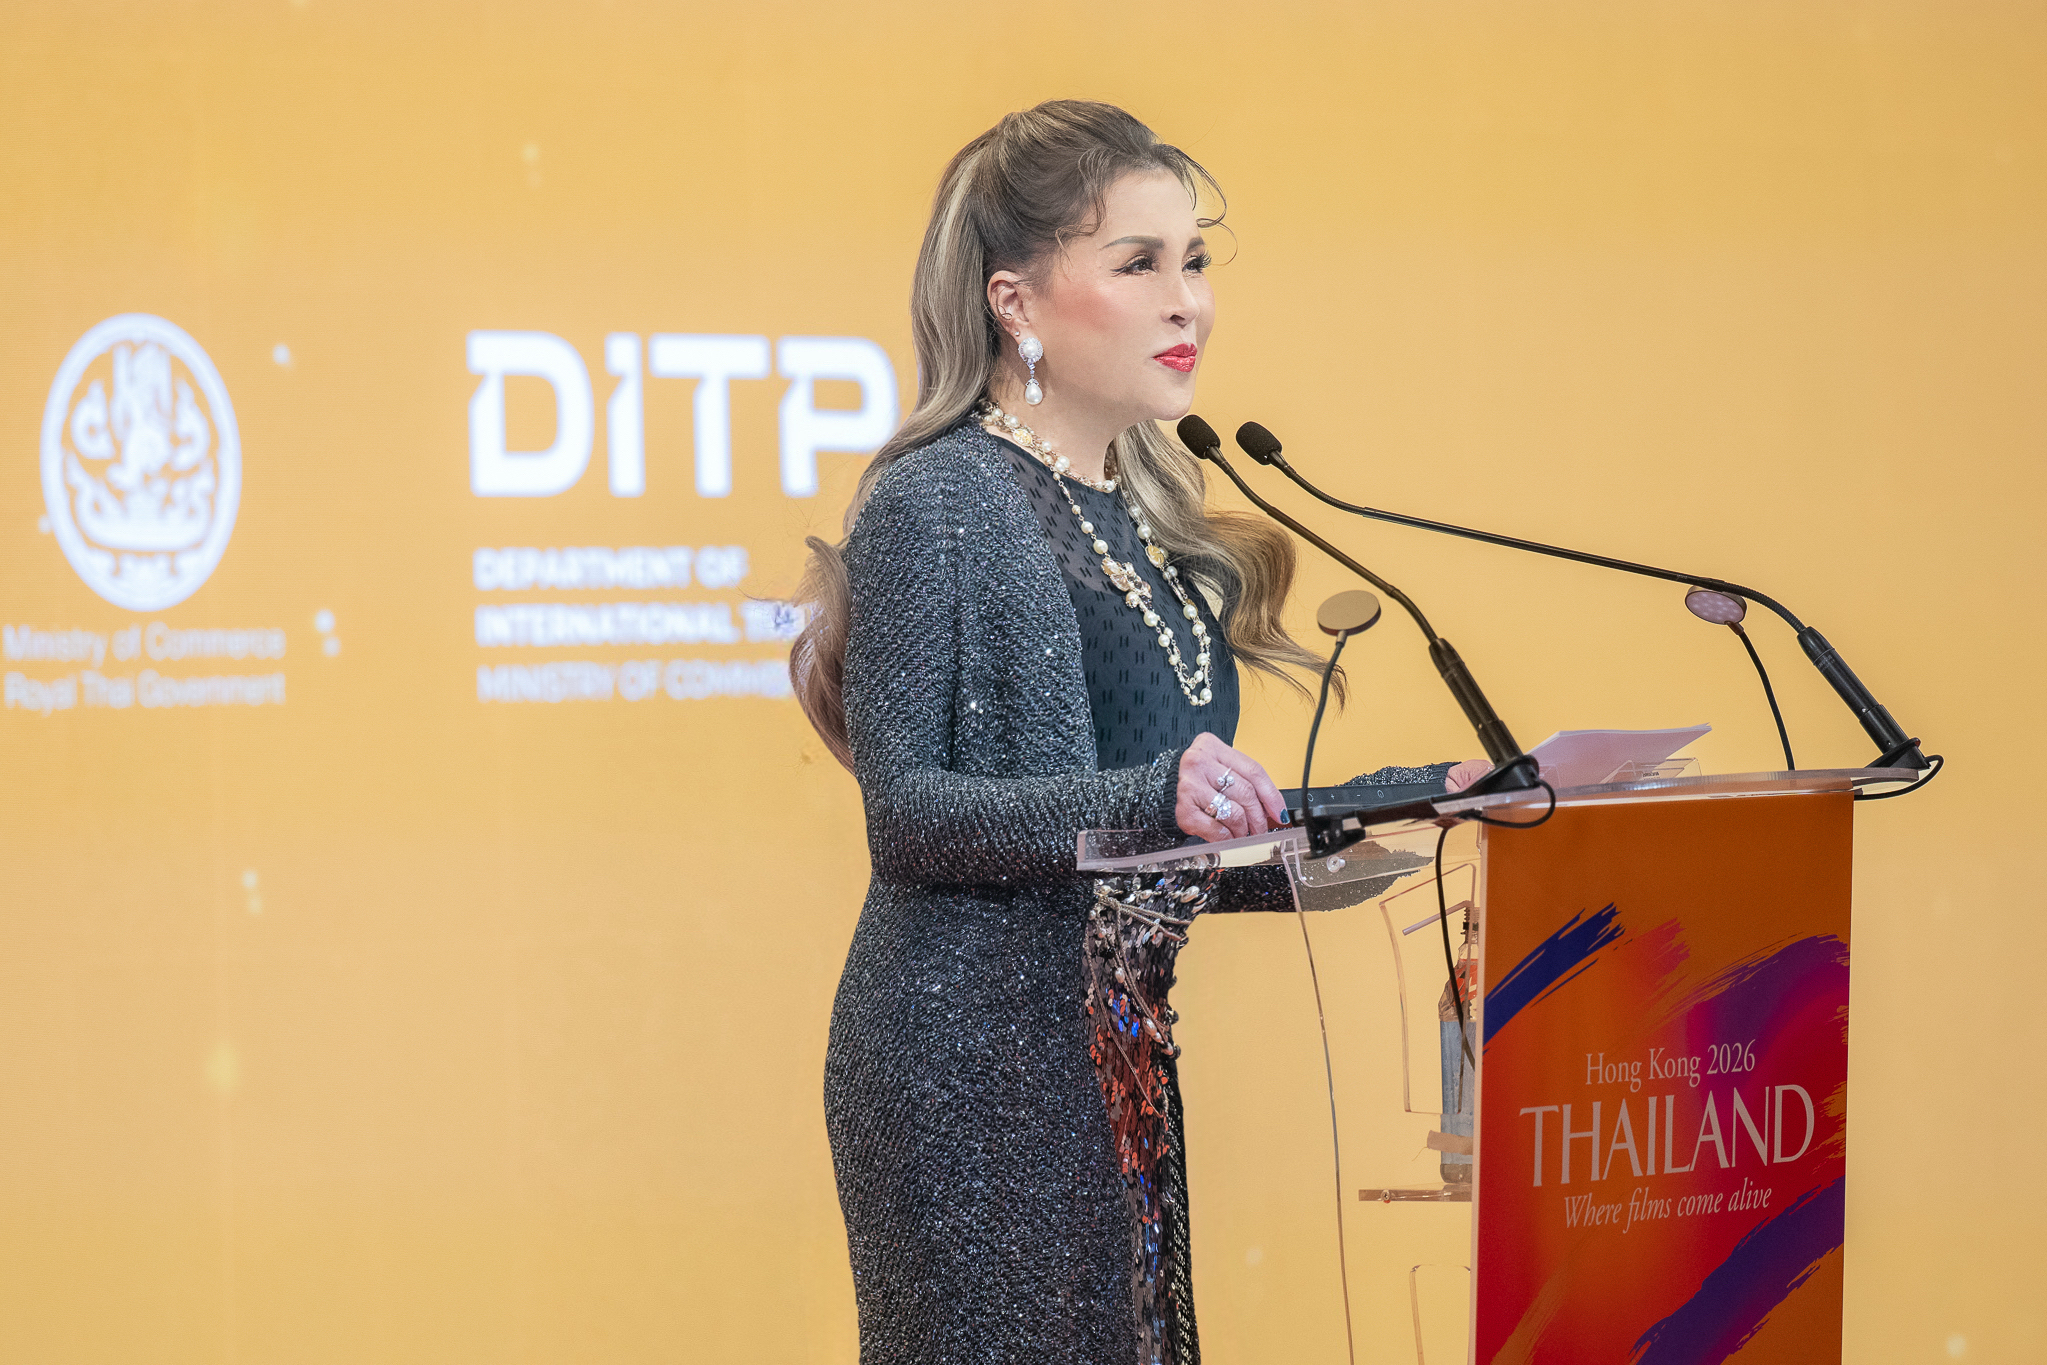
HONG KONG SAR – Media OutReach Newswire – 25 March 2026 – The Department of International Trade Promotion (DITP), Ministry of Commerce, successfully hosted “Thai Night Hong Kong 2026” on 18 March 2026 at the Ballroom, JW Marriott Hong Kong, Hong Kong Special Administrative Region of the People’s Republic of China. The event aimed to foster business networking and promote collaboration between Thai entrepreneurs and international partners in the film and entertainment industry, with over 517 participants from across the global entertainment sector, including investors, content creators, and media representatives.

Image 1

The event was graciously presided over by Her Royal Highness Princess Ubolratana Rajakanya Sirivadhana Barnavadi, who continues to play a vital role in supporting and promoting Thailand’s film and entertainment industry on the global stage. The occasion also provided a valuable platform for Thai entrepreneurs to expand business opportunities and strengthen international partnerships.

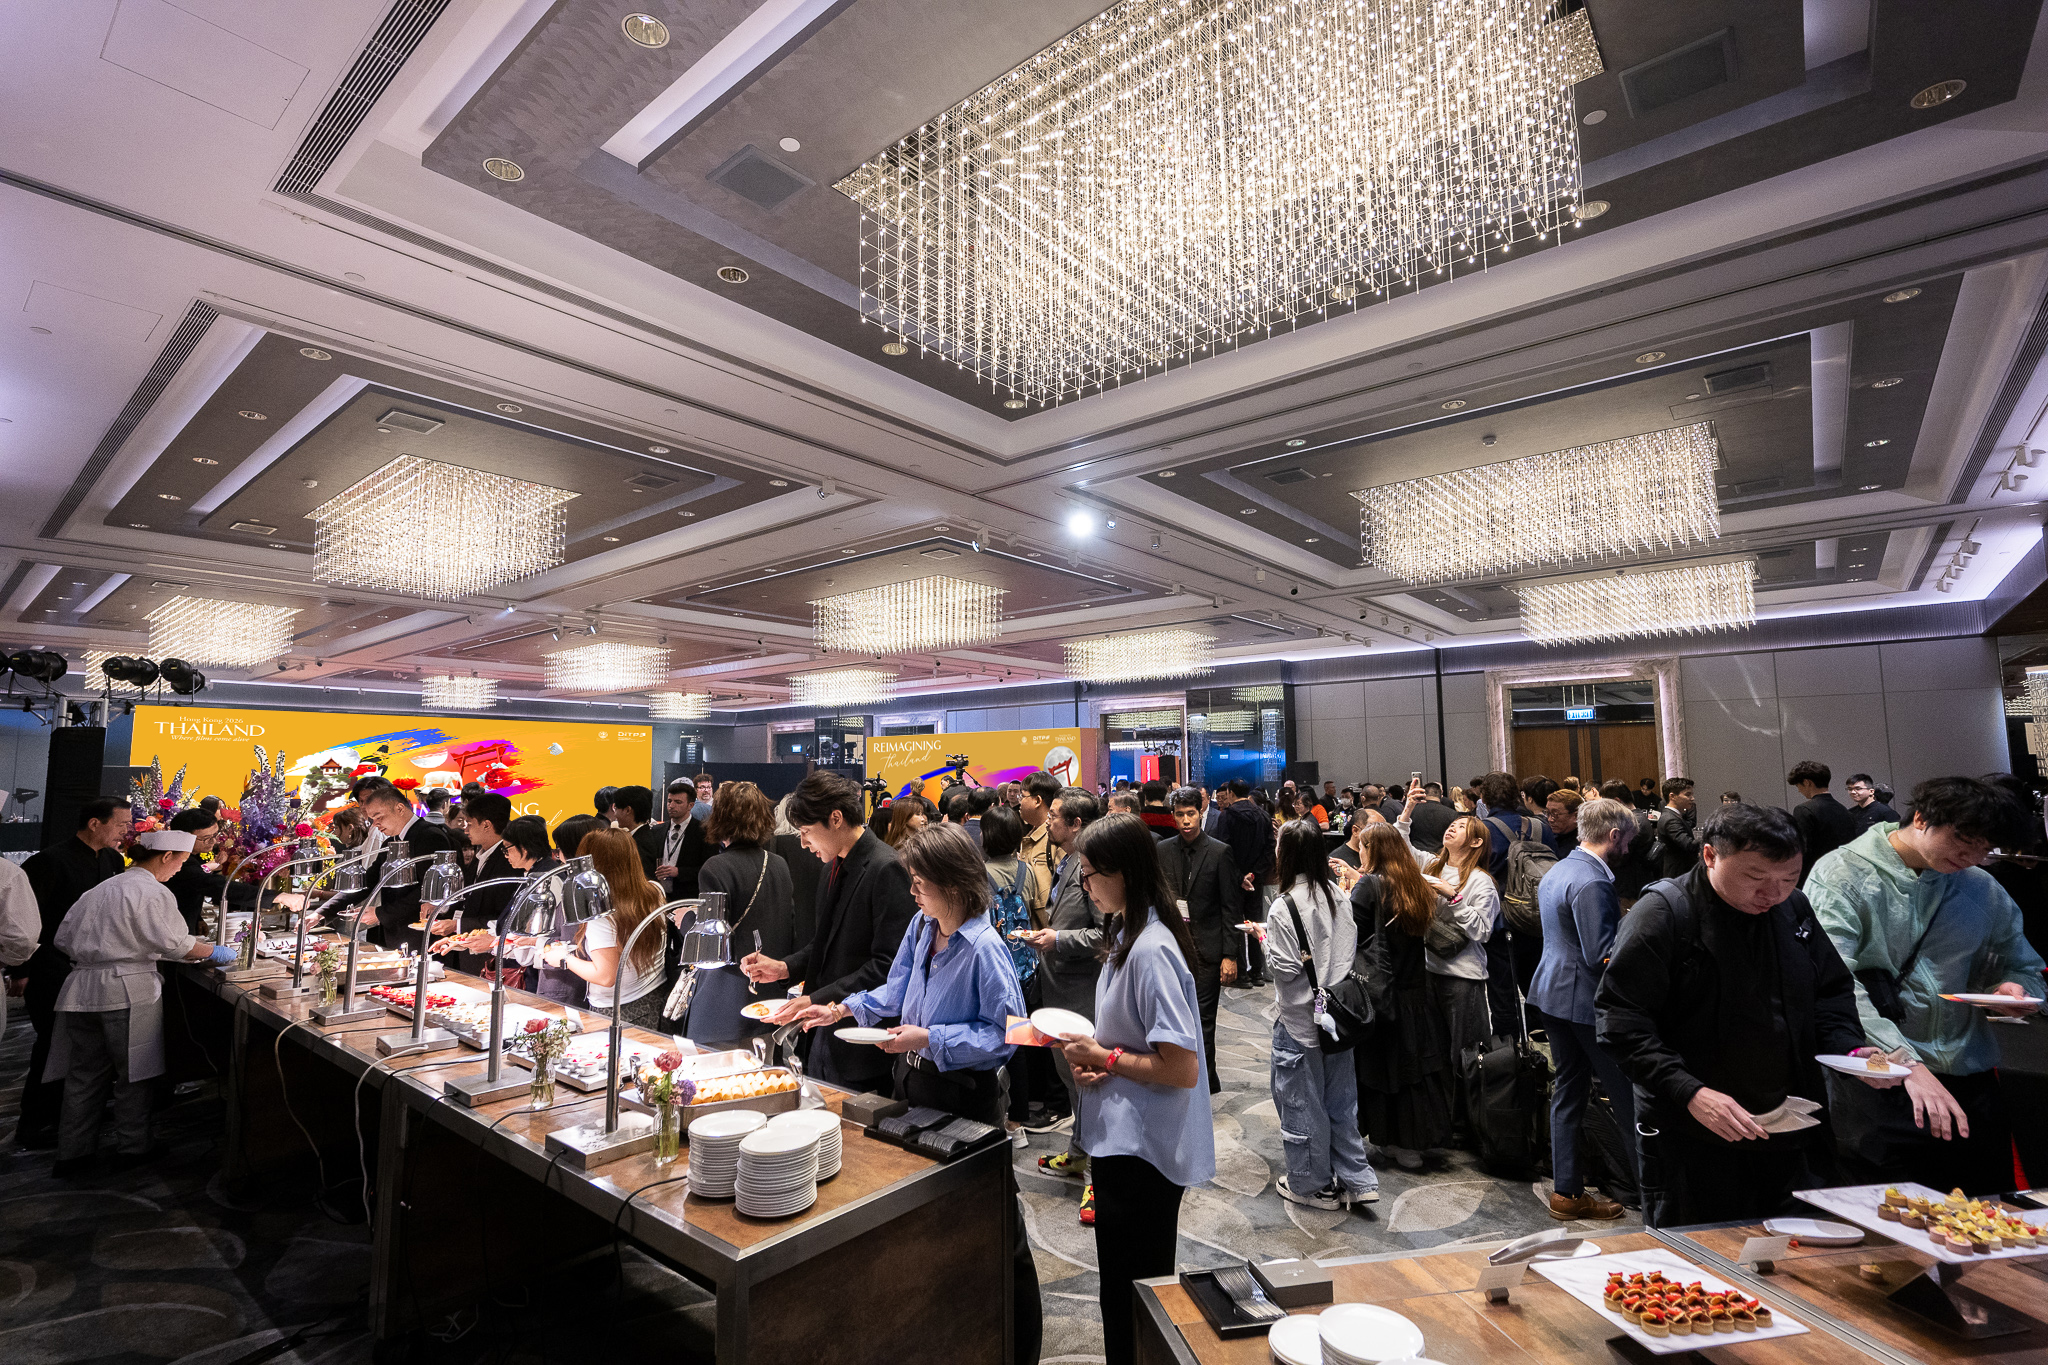
Image 2

Thai Night Hong Kong 2026 was held alongside the Hong Kong International Film & TV Market (FILMART) 2026, one of Asia’s leading marketplaces for film and television content. The event served as a platform to celebrate the achievements of Thailand’s entertainment industry while showcasing the capabilities of Thai content creators to global buyers, investors, and industry stakeholders.

This year’s event was presented under the theme “Reimagining Thailand”, highlighting Thailand as a comprehensive creative destination for film and entertainment production. The concept reflects the country’s strengths in skilled talent, diverse filming locations, internationally recognized production standards, and advanced post-production capabilities.

The atmosphere of the event was vibrant and dynamic, with participants from various countries engaging in discussions, exchanging insights, and exploring opportunities for co-production and investment within Thailand’s entertainment sector.

In addition, the event featured live performances by Thai entertainment industry players, demonstrating the creativity and production excellence of Thai content. These performances blended contemporary storytelling with cultural identity, leaving a strong impression on international attendees and reinforcing Thailand’s position as a compelling creative partner on the global stage.

Image 3

The successful organization of Thai Night Hong Kong 2026 reflects growing international interest in Thailand’s entertainment industry and underscores its potential as a key player in the global content landscape. The event also served as an important platform for Thai entrepreneurs to expand their market reach and build sustainable partnerships with international stakeholders.

Hashtag: #DITP

The issuer is solely responsible for the content of this announcement.

VERIGRAFT Advances First Potential Curative Treatment for CVI into Pivotal Phase II/III Trial

  • Pivotal Phase II/III clinical trial underway, aiming for US and European market approval in 2028
  • A ‘truly transformative’ regenerative medicine targeting a multi-million patient population with no existing curative treatment
  • Fully biological transplant eliminates need for immunosuppression and restores natural function
  • Scalable process protected by 92 granted patents
  • CVI market projected to reach USD 5,951 million by 2034*
  • Supported by USD 10 million financing from existing investors

GOTHENBURG, Sweden, March 25, 2026 /PRNewswire/ — VERIGRAFT, a Swedish clinical-stage biotechnology company pioneering personalized, fully biological therapies, today announced the initiation of a pivotal Phase II/III trial of its P-TEV (personalized tissue engineered vein) in patients with chronic venous insufficiency (CVI), supported by USD 10 million from existing investors.

The milestone comes at a time when regenerative medicine and personalized biologics are gaining significant traction among global investors and healthcare systems.

VERIGRAFT’s fully biological approach opens the way for a potential curative treatment for CVI, using personalized tissues that eliminates the need for immunosuppressive therapy. The manufacturing process is completed within 10 days, making VERIGRAFT’s offering both scalable and clinically feasible. Trial sites for the Phase II/III study are located in Spain, the Netherlands and Poland.

As an advanced therapy medicinal product (ATMP), VERIGRAFT’s clinical development programme is designed to generate robust clinical data in a limited patient population. The Company aims to achieve market approval in Europe and the US in 2028.

Chronic Venous Insufficiency (CVI) is a progressive and under-recognized vascular disease in which the veins in the legs fail to efficiently return blood to the heart, leading to sustained elevated venous pressure in the leg veins. Driven by factors such as ageing, obesity, and sedentary lifestyles, CVI represents a growing healthcare burden worldwide.

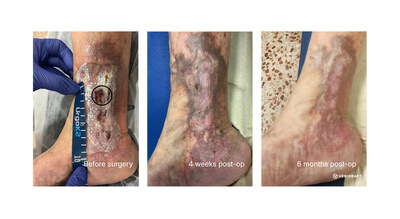
VERIGRAFT’s personalized tissue-engineered vein (P-TEV) is designed to replace diseased venous segments with dysfunctional valves with vein segments containing functioning valves. The approach uses donor-derived venous material that is decellularized and subsequently personalized using the patient’s own blood, creating a patient-specific graft. Once prepared, the P-TEV is surgically implanted to replace the diseased vein segment and restore venous function.

Petter Björquist, CEO of VERIGRAFT, said: “This financing enables a critical step forward in our clinical development and is a critical component in our journey to redefine how vascular disease can be treated by restoring natural biological function at scale. With P-TEV, we are addressing a large, underserved patient population with a therapy designed to address the underlying cause of disease, not just manage the symptoms. The initiation of our pivotal trial brings us significantly closer to making this a clinical reality.”

Dr. Bryan Kluck, an Interventional Cardiologist, Endovascular Interventionalist and Vascular Medicine Specialist at Lehigh Valley Hospital, Allentown, PA, commented: “As an interventional cardiologist familiar with the technology, I believe it offers a new way forward. This is truly restorative, unlike so many of the available tools. Patency of the venous system, along with functional vein valves, has the potential to revolutionize venous therapy. This technology restores normal venous hemodynamics, a concept that, heretofore has been unimaginable.”

Dr. Andrés García León, Head of the Department of Angiology and Vascular Surgery at Virgen de Valme University Hospital, Associate Professor of the University of Seville, and Lead Principal Investigator (PI), added: “I am very pleased to be leading the phase II/III trial of P-TEV. In clinical practice, treatment options for patients with advanced CVI are limited. P-TEV represents a promising and scalable approach with the potential to restore physiological blood flow.”

*Chronic Venous Insufficiency Market Insight, Epidemiology And Market Forecast – 2034
Source: DelveInsight

Visit www.verigraft.com

Photo: https://laotiantimes.com/wp-content/uploads/2026/03/verigraft_p_tev.jpg
Logo: https://laotiantimes.com/wp-content/uploads/2026/03/verigraft_logo.jpg


Restorative effect of replacing diseased vein with fully biological P-TEV personalized tissue engineered vein

Ananda Launches Relocation Platform, Positioning Thailand as Asia’s Preferred Base for Global Living

‘One-Stop-Service’ Platform for Families and Investors Seeking Stability and Opportunity throughout Southeast Asia


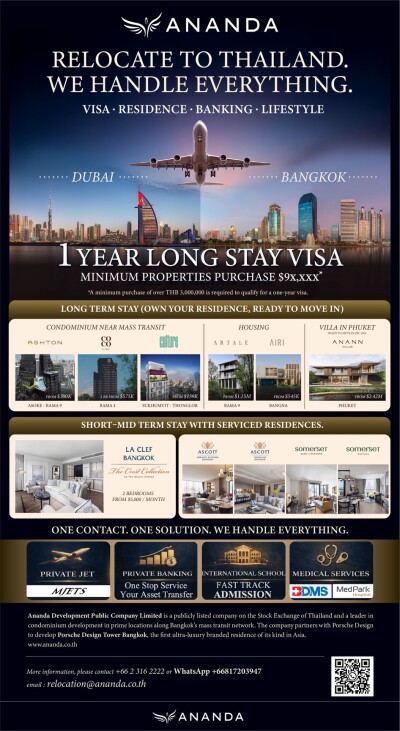
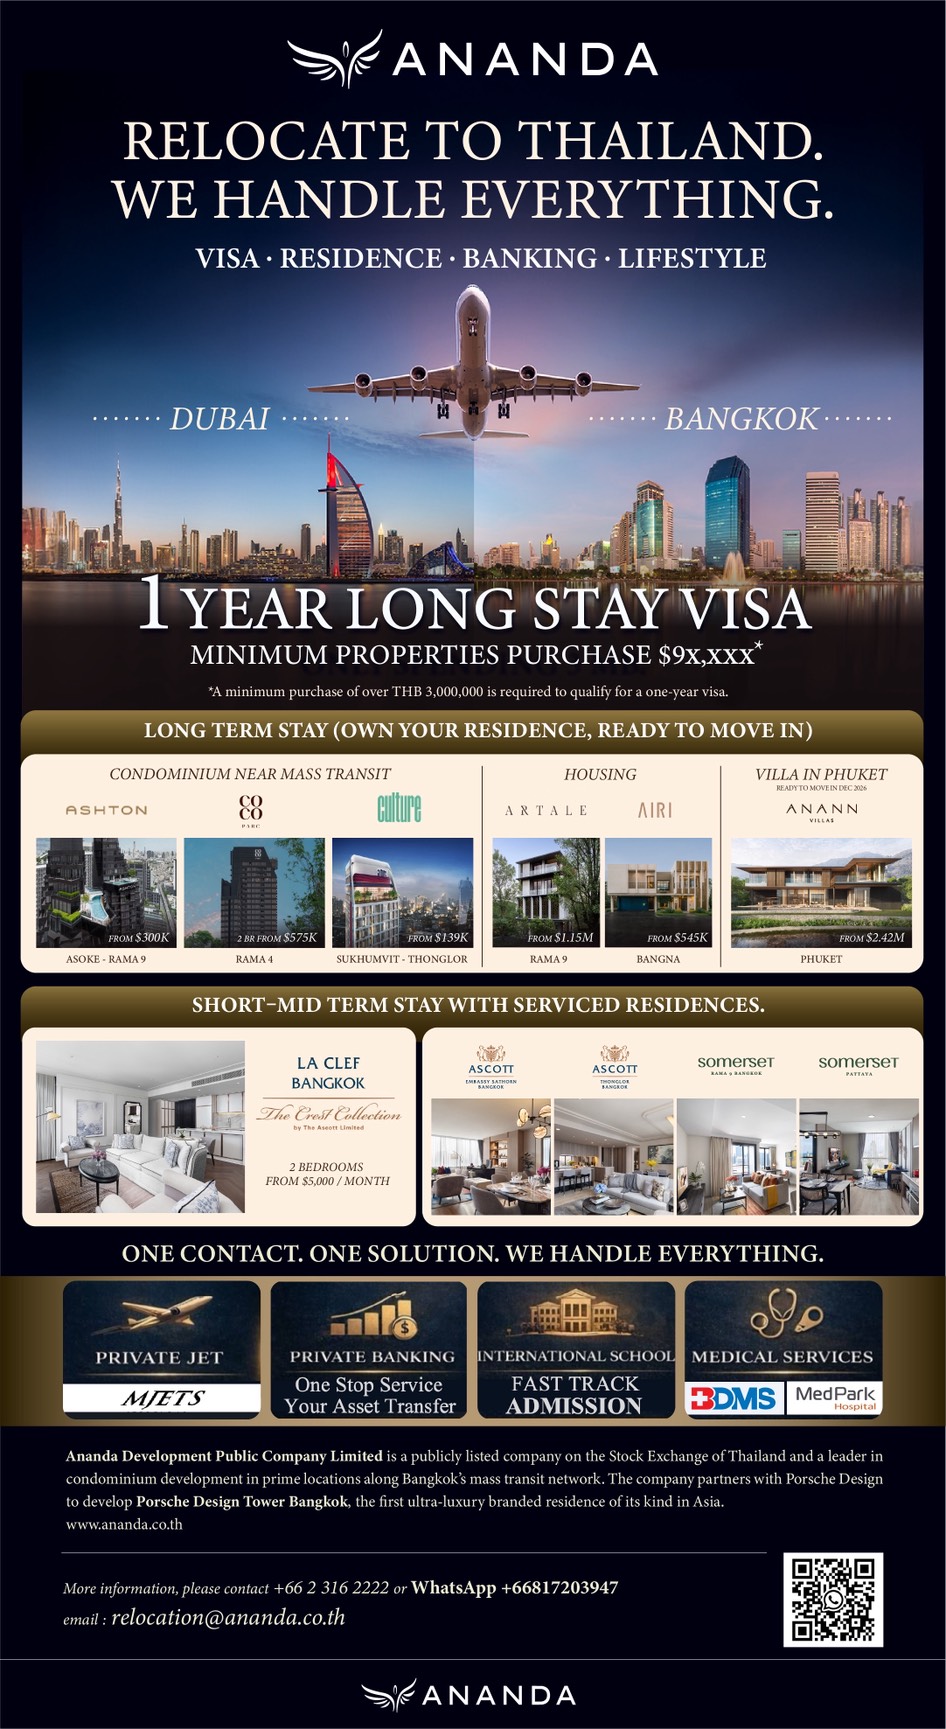
BANGKOK, THAILAND – Media OutReach Newswire – 25 March 2026 – In response to growing geopolitical uncertainty, Ananda Development, a publicly listed Thai company and leading developer of urban residences including the landmark Porsche Design Tower Bangkok, today announced the launch of Ananda Relocation Services. This comprehensive, integrated platform is designed to provide a secure, stable, and luxurious base in Thailand for international families, professionals, and investors seeking peace of mind and long-term resilience.

Ananda Relocation Services

A Fully Integrated, One-Stop Solution

Ananda Relocation Services is designed as a fully integrated ecosystem to eliminate the complexities of moving abroad. Through a single point of contact, the platform provides coordinated access to a comprehensive range of services, including private jet transfer arrangements, private banking and wealth management coordination, access to leading international schools, and world-class healthcare services.

The platform provides a wide array of residency solutions, from premium serviced residences for short- to mid-term stays through leading operators such as La Clef, Ascott, and Somerset, to long-term home ownership opportunities. These range from condominiums near Bangkok’s mass transit network to luxury housing and high-end villas in Phuket. Notably, the program offers one-year long-term visa support for property purchases starting from THB 3,000,000 (Approx. $9x,xxx USD), creating a clear and simple path to residency.

Bangkok as a Thriving Global Hub

Bangkok has firmly established itself as one of Asia’s most attractive cities and a preferred destination for global citizens. The city is a vibrant hub of opportunity, offering unparalleled global connectivity that makes it a strategic second base. Its unique appeal lies in a dynamic blend of rich global cultures and a famously welcoming atmosphere that draws residents into a city full of life.

The city’s world-class infrastructure—including its robust banking sector, leading international schools, and premier healthcare systems—is a key factor that increasingly attracts global professionals, investors, and families seeking a new base. Ananda Relocation Services is designed to manage and facilitate every detail of the process to ensure a smooth transition, offering a truly seamless experience. While Bangkok serves as the primary gateway, the service also creates opportunities in other world-renowned destinations in Thailand.

Mr. Chanond Ruangkritya, Chief Executive Officer of Ananda Development, stated, “Bangkok has all the right fundamentals to become one of Asia’s most welcoming and strategic bases for international residents. Our relocation platform is designed to offer genuine peace of mind during a complex time with a seamless, worry-free transition experience for families and investors. By integrating residences, mobility, healthcare, education, and lifestyle services, we enable global citizens to establish themselves in Bangkok with confidence.”

He added, “This initiative aligns with Thailand’s increasing relevance in the global mobility landscape, as more individuals seek destinations that offer resilience, openness, and long-term livability.”

For individuals and families interested in relocating to Thailand or exploring residence and lifestyle opportunities with Ananda, please contact:

Ananda Relocation Services

Tel: +66 2 316 2222
WhatsApp: +66 81 720 3947
Email: relocation@ananda.co.th
Website: www.ananda.co.th

Hashtag: #Ananda

The issuer is solely responsible for the content of this announcement.

About Ananda Development

Ananda Development Public Company Limited is a leading real estate developer listed on the Stock Exchange of Thailand, specializing in residential developments in prime urban locations along Bangkok’s mass transit network. The company is recognized for its innovative approach to urban living, integrating design, connectivity, and lifestyle into its developments. Ananda has also partnered with Porsche Design to develop Porsche Design Tower Bangkok, marking the first ultra-luxury branded residence of its kind in Asia. Through continuous innovation, Ananda is expanding beyond conventional real estate into integrated living ecosystems that respond to the evolving needs of modern global citizens.

DPC Dash Ltd Announces Full Year 2025 Financial Results

Revenues increased to RMB5.38 billion, representing 24.8% year-over-year growth

Adjusted net profit reached RMB187.9 million, representing 43.3% year-over-year growth

Store-level operating profit grew by 18.5%; Adjusted group EBITDA increased by 28.2%

EPS increased 157.1% YoY to RMB1.08, Diluted EPS increased 150.0% YoY to RMB1.05

HONG KONG, March 25, 2026 /PRNewswire/ — DPC Dash Ltd – Domino’s Pizza China (“DPC Dash” or the “Company”, together with its subsidiaries, the “Group”) (1405.HK), Domino’s Pizza’s exclusive master franchisee in the China Mainland, the Hong Kong Special Administrative Region of China, and the Macau Special Administrative Region of China, today announced its audited consolidated financial results for the year ended December 31, 2025 (“FY2025”).

FY2025 HIGHLIGHTS[1]

  • Revenues reached RMB5.38 billion, representing an increase of 24.8% from RMB4.31 billion in the year ended December 31, 2024 (“FY2024”).
  • Opened 307 net new stores and entered into 21 new cities in FY2025. Total stores reached 1,315, across 60 cities, with 517 stores in Tier 1 cities and 798 stores in non-Tier 1 cities, as of December 31, 2025.
  • Same-store sales growth (SSSG) was -1.5%, compared to 2.5% for FY2024 and -1.0% in the first six months of 2025. Tier 1 City markets delivered positive SSSG during FY2025 and in both the six months ended June 30 and December 31, 2025.
  • Store-level EBITDA was RMB1,001.0 million, representing an increase of 20.4% from RMB831.4 million in FY2024. Store-level EBITDA margin was 18.6%, compared to 19.3% in FY2024.
  • Store-level operating profit was RMB739.7 million, representing an increase of 18.5% from RMB624.0 million in FY2024. Store-level operating profit margin was 13.7%, compared to 14.5% for FY2024.
  • Adjusted EBITDA was RMB634.6 million, representing an increase of 28.2% from RMB495.2 million in FY2024. Adjusted EBITDA margin was 11.8%, compared to 11.5% for FY2024.
  • Adjusted Net profit was RMB187.9 million, representing an increase of 43.3% from RMB131.2 million in FY2024. Adjusted Net Profit margin was 3.5%, compared to 3.0% for FY2024.
  • As of December 31, 2025, the Group held RMB1,001.5 million in cash and bank balances, as compared to RMB1,069.3 million as of December 31, 2024.
  • Total loyalty program membership was 35.6 million, representing an increase of 45.3% from 24.5 million in FY2024.

[1] Please refer to the section “KEY DEFINITIONS” below for detailed definitions on certain terms used.

Ms. Aileen Wang, CEO & Executive Director of DPC Dash commented, “We delivered another year of strong growth in 2025, with revenue increasing 24.8% to RMB5.38 billion and 307 net store openings expanding our footprint to 1,315 stores across 60 cities as of year end. Our 4D strategy continues to drive results across our network. Stores in Tier 1 cities delivered solid growth driven by positive same-store sales growth, demonstrating the resilience and sustained brand strength in our most mature markets. Meanwhile, non-Tier 1 markets now contribute nearly 60% of revenue, with new stores achieving exceptional unit economics and strong capital efficiency. We remain confident in our ability to capture the significant pizza market opportunity while delivering sustainable, long-term value for our shareholders.”

Ms. Helen Wu, CFO of DPC Dash, added, “Our 2025 results reflect both strong top-line momentum and enhanced operating efficiency, with adjusted EBITDA growing 28.2% to RMB634.6 million and adjusted net profit increasing 43.3% to RMB187.9 million. These results reflect our consistent cost discipline and targeted store‑level investments, as well as the increasing benefits of scale and efficiency at the corporate level. Looking ahead, supported by our solid balance sheet, we are well positioned to advance our ‘Go‑Deeper’ and ‘Go‑Broader’ strategy in a disciplined manner, maintaining a strong focus on efficiency as our footprint expands and stores ramp up.”

FY2025 Financial Results

Year ended

Dec 31,

Dec 31,

(in RMB millions, except percentages and per share data)

2025

2024

YoY

Revenue

5,382.0

4,314.1

+24.8 %

Store-level EBITDA[1]

1,001.0

831.4

+20.4 %

Store-level EBITDA margin[1]

18.6 %

19.3 %

-0.7

Store-level operating profit

739.7

624.0

+18.5 %

Store-level operating profit margin

13.7 %

14.5 %

-0.8

Adjusted EBITDA[1]

634.6

495.2

+28.2 %

Adjusted EBITDA margin[1]

11.8 %

11.5 %

+0.3

Adjusted Net Profit[1]

187.9

131.2

+43.3 %

Adjusted Net Profit margin[1]

3.5 %

3.0 %

+0.5

Net Profit

141.9

55.2

157.1 %

Net Profit margin

2.6 %

1.3 %

+1.3

Basic Earnings per share

1.08

0.42

157.1 %

Diluted Earnings per share

1.05

0.42

150.0 %

[1] Please refer to the section “Non-IFRS Measures” below for detailed definition on certain terms used.

Recent Developments

On December 19, 2025, the Company was recognized as a 2025 Best Employer by Mercer for the fourth consecutive year, and was also honored with the first-time “Star Employer” award.

As of December 31, 2025, the Chinese mainland market ranks as the third-largest international market within Domino’s Pizza’s global system in terms of store count.

On January 1, 2026, the Company opened 62 stores in 46 cities, the highest daily opening record in its history. Its first store in Dalian generated sales close to RMB700,000 on the grand opening day, setting a new record in Domino’s global system.

As of January 31, 2026, the Company held all of the top 50 positions in the global records of Domino’s Pizza for the first 30-day sales of new stores, such as the first store in Xuzhou, Handan and Huhehaote.

Outlook

The Group expects to open approximately 350 new stores in 2026. As of March 20, 2026, the Company opened 140 net new stores, with 14 stores under construction, and 65 stores signed, well on track to deliver the 2026 full year opening target of 350 stores.

Conference Call Information

The Company will host a conference call today, Wednesday, March 25, 2026, at 7:00 pm Hong Kong Time (or Wednesday, March 25, 2026, at 7:00 am Eastern Time) to discuss the financial results.

A live audio-only webcast of the call can be accessed directly at https://event.choruscall.com/mediaframe/webcast.html?webcastid=nHRXnD0d.

To participate by phone, participants are strongly encouraged to pre-register for the conference call, by using the link provided below. Upon registering, each participant will receive a set of participant dial-in numbers, the event passcode, and a unique access PIN, which can be used to join the conference call.

Pre-registration Link: https://dpregister.com/sreg/10206649/1034ed20f15

An audio-only replay of the call will also be accessible through April 1, 2026, by dialing the following numbers:

United States Toll Free:

+ 1-855-669-9658

International:

+ 1-412-317-0088

Access Code:

2877882

Key Definitions

  • Store-level operating profit represents revenue less operational costs incurred at the store level, comprising salary-based expense, raw materials and consumables cost, depreciation of right-of-use assets, depreciation of plant and equipment, amortization of intangible assets, variable lease rental payment and short-term rental expenses, utilities expenses, advertising and promotion expenses, store operating and maintenance expenses and other expenses.
  • Store-level operating profit margin is calculated by dividing store-level operating profit by revenue for the same year.
  • Store-level EBITDA is defined as store-level operating profit for the year and adding back depreciation of plant and equipment and amortization of intangible assets in store-level.
  • Store-level EBITDA margin is calculated by dividing Store-level EBITDA by revenue for the same year.
  • Adjusted EBITDA is defined as Adjusted Net Profit for the year and adding back depreciation and amortization (excluding depreciation of right-of-use assets), income tax expense and interest income and expenses, net.
  • Adjusted EBITDA margin is calculated by dividing Adjusted EBITDA by revenue for the same year.
  • Adjusted Net Profit is defined as profit for the year and adding back share-based compensation.
  • Adjusted Net Profit margin is calculated by dividing Adjusted Net Profit by revenue for the same year.
  • Net new store openings. The number of gross new stores opened during the year minus the number of stores closed during the period.
  • Same-store sales growth (SSSG). SSSG compares the sales generated by same stores during the relevant period year-on-year: the SSSG for the year ended December 31, 2025 compares the same-store sales of the year ended December 31, 2025 and that of the year ended December 31, 2024; the SSSG for the six months ended June 30, 2025 compares the same-store sales of the six months ended June 30, 2025 and that of the six months ended June 30, 2024; and the SSSG for the year ended December 31, 2024 compares the same-store sales of the year ended December 31, 2024 and that of the year ended December 31, 2023.

Non-IFRS Measures

To supplement the Group’s consolidated financial statements that are presented in accordance with the IFRS, the Group also uses Adjusted Net Profit (non-IFRS measure), Adjusted Net Profit margin (non-IFRS measure), Adjusted EBITDA (non-IFRS measure), Adjusted EBITDA margin (non-IFRS measure), Store-level EBITDA (non-IFRS measure) and Store-level EBITDA margin (non-IFRS measure) as additional financial measures, which are not required by, or presented in accordance with, IFRS.

“Store-level EBITDA” is defined as store-level operating profit for the year and adding back depreciation of plant and equipment and amortization of intangible assets in store-level. “Store-level EBITDA margin” is calculated by dividing Store-level EBITDA by revenue for the same year. “Adjusted Net Profit” is defined as profit for the year and adding back share-based compensation. “Adjusted Net Profit margin” is calculated by dividing Adjusted Net Profit by revenue for the same year. “Adjusted EBITDA” is defined as Adjusted Net Profit for the year and adding back depreciation and amortization (excluding depreciation of right-of-use assets), income tax expense and interest income and expenses, net. “Adjusted EBITDA margin” is calculated by dividing Adjusted EBITDA by revenue for the same year.

The Group believes that these non-IFRS measures facilitate comparisons of operating performance from period to period and company to company. The Group believes that these measures provide useful information to investors and others in understanding and evaluating the Group’s results of operations in the same manner as they help the Group’s management. However, the Group’s presentation of Adjusted Net Profit (non-IFRS measure), Adjusted Net Profit margin (non-IFRS measure), Adjusted EBITDA (non-IFRS measure), Adjusted EBITDA margin (non-IFRS measure), Store-level EBITDA (non-IFRS measure) and Store-level EBITDA margin (non-IFRS measure) may not be comparable to similarly titled measures presented by other companies. The use of such non-IFRS measures has limitations as an analytical tool, and shareholders and potential investors of the Company should not consider them in isolation from, or as substitute for analysis of, the Group’s results of operations or financial condition as reported under IFRS.

Forward-Looking Statements

Certain statements in this document and/or the Announcement are forward-looking statements that are, by their nature, subject to significant risks and uncertainties. Any statements that express, or involve discussions as to, expectations, beliefs, plans, objectives, assumptions, future events, or performance (often, but not always, through the use of words or phrases such as “will”, “expect”, “anticipate”, “estimate”, “believe”, “going forward”, “ought to”, “may”, “seek”, “should”, “intend”, “plan”, “projection”, “could”, “vision”, “goals”, “aim”, “aspire”, “objective”, “target”, “schedules”, and “outlook”) are not historical facts, are forward-looking and may involve estimates and assumptions and are subject to risks (including but not limited to the risk factors detailed in this document and/or the Announcement), uncertainties and other factors some of which are beyond the Company’s control. Accordingly, these factors could cause actual results or outcomes to differ materially from those expressed in the forward-looking statements. The Company’s forward-looking statements have been based on assumptions and factors concerning future events that may prove to be inaccurate. Those assumptions and factors are based on information currently available to the Company about the businesses that it operates. The risks, uncertainties and other factors, many of which are beyond the Company’s control, that could influence actual results include, but are not limited to: the Company’s operations and business prospects; its business and operating strategies and ability to implement such strategies; its ability to develop and manage its operations and business; its ability to control costs and expenses; its ability to identify and satisfy customer demands and preferences; the actions and developments of its competitors; general economic, political and business conditions in the markets in which it operates; and changes to regulatory and operating conditions in the industry and geographical markets in which it operates.

Any forward-looking statement speaks only as of the date on which such statement is made, and, except as required by the Rules Governing the Listing of Securities on The Stock Exchange of Hong Kong Limited or under applicable law, the Company undertakes no obligation to update any forward-looking statement to reflect events or circumstances after the date on which such statement is made or to reflect the occurrence of unanticipated events.

Since actual results or outcomes could differ materially from those expressed in any forward-looking statements, the Company’s shareholders and potential investors are advised not to place undue reliance on the forward-looking statements and to exercise caution in dealing in securities in the Company.

About DPC Dash Ltd

DPC Dash is Domino’s Pizza’s exclusive master franchisee in the Chinese mainland, the Hong Kong Special Administrative Region of China and the Macau Special Administrative Region of China. Domino’s Pizza, Inc., DPC Dash’s global franchisor, is one of the most widely-recognized global consumer brands and the world’s largest pizza company. Led by a seasoned and visionary management team, DPC Dash is a market leader that differentiates from competitors with, among others, a continually innovated and localized pizza-focused menu, unique expertise and leadership in delivery, technology focus and scalable and replicable store economic model. DPC Dash operates 1,315 stores in 60 cities in the Chinese mainland as of December 31, 2025.

For more information, please visit www.dpcdash.com
For official company announcements, please visit www.hkexnews.hk

Contacts
DPC Dash Ltd Investor Relations:
DPC Dash Ltd
IR@dominos.com.cn

CONSOLIDATED STATEMENT OF COMPREHENSIVE INCOME

Year ended December 31

2025

2024

RMB’000

RMB’000

Revenue

5,382,047

4,314,093

Raw materials and consumables cost

(1,469,005)

(1,169,799)

Staff compensation expenses

(1,829,886)

(1,509,483)

Depreciation of right-of-use assets

(395,397)

(307,139)

Depreciation of plant and equipment

(261,405)

(208,643)

Amortization of intangible assets

(58,755)

(54,104)

Utilities expenses

(196,772)

(164,104)

Advertising and promotion expenses

(269,236)

(217,623)

Store operation and maintenance expenses

(334,184)

(270,833)

Variable lease rental payment, short-term
   rental and other related expenses

(144,493)

(121,035)

Other expenses

(160,082)

(137,721)

Other income

18,951

14,560

Other losses, net

(13,861)

(10,589)

Finance costs, net

(64,920)

(57,975)

Profit before income tax

203,002

99,605

Income tax expense

(61,070)

(44,410)

Profit for the year attributable to equity
   holders
of the Company

141,932

55,195

Other comprehensive (loss)/income:

Item that may be subsequently reclassified to   
profit or loss

Currency translation differences

10,951

(4,670)

Item that may not be subsequently reclassified
   to profit or loss

Currency translation differences

(21,534)

13,583

Other comprehensive (loss)/income for the
   year, net of tax

(10,583)

8,913

Total comprehensive income for the year
   attributable to equity holders of the
   Company

131,349

64,108

Earnings per share for profit attributable to
   equity holders of the Company

– Basic earnings per share (RMB)

1.08

0.42

– Diluted earnings per share (RMB)

1.05

0.42


CONSOLIDATED BALANCE SHEET

As at December 31

2025

2024

RMB’000

RMB’000

ASSETS

   Non-current assets

Plant and equipment

1,038,359

807,812

Right-of-use assets

1,747,209

1,305,383

Intangible assets

1,208,671

1,211,213

Deposits

104,798

74,822

Deferred income tax assets

161,863

108,336

4,260,900

3,507,566

Current assets

Inventories

132,065

114,551

Trade receivables

17,349

12,962

Prepayment, deposits and other receivables

234,766

171,745

Cash and bank balances

1,001,511

1,069,302

1,385,691

1,368,560

Total assets

5,646,591

4,876,126

EQUITY

Equity attributable to equity holders of the
   Company

Share capital

888,950

882,537

Share premium

2,324,731

2,278,503

Other reserves

148,368

150,240

Accumulated losses

(925,122)

(1,067,054)

Shares held for restricted share units

(“RSUs”)

(525)

(994)

Total equity

2,436,402

2,243,232

LIABILITIES

Non-current liabilities

Borrowings

199,400

–

Lease liabilities

1,413,606

1,078,957

Other payables

60,178

36,939

1,673,184

1,115,896

Current liabilities

Borrowings

400

200,000

Lease liabilities

393,684

289,221

Trade payables

279,126

248,645

Contract liabilities

56,008

63,010

Accruals and other payables

778,543

676,051

Current income tax liabilities

29,244

40,071

1,537,005

1,516,998

Total liabilities

3,210,189

2,632,894

Total equity and liabilities

5,646,591

4,876,126


CONSOLIDATED CASH FLOW STATEMENT

Year ended December 31

2025

2024

RMB’000

RMB’000

Cash flows from operating activities

Cash generated from operations

1,018,322

895,890

Income tax paid

(125,423)

(77,469)

Net cash generated from operating activities

892,899

818,421

Cash flows from investing activities

Purchase of plant and equipment

(454,304)

(373,163)

Purchase of intangible assets

(51,724)

(43,082)

Interest received

17,503

25,288

Proceeds from disposal of plant and
   equipment

48

127

Decrease in short-term time deposits with
   original maturities over three months

–

432,444

Net cash (used in)/generated from investing
   activities

(488,477)

41,614

Cash flows from financing activities

Rental deposit payment

(28,724)

(24,608)

Proceeds from borrowings

200,000

–

Repayment to borrowings

(200,200)

–

Payment of principal element of lease
   liabilities

(370,212)

(285,213)

Payment of interest element of lease
   liabilities

(74,024)

(68,092)

Interests paid

(6,584)

(9,318)

Proceeds from exercise of share options

15,853

5,225

Net cash used in financing activities

(463,891)

(382,006)

Net (decrease)/increase in cash and cash
   equivalents

(59,469)

478,029

Cash and cash equivalents at beginning of
   year

1,069,102

587,038

Exchange difference on cash and cash
   equivalents

(8,322)

4,035

Cash and cash equivalents at end of year

1,001,311

1,069,102

Cash at bank and in hand at end of year

1,001,511

1,069,302

Less: Restricted cash at end of year

(200)

(200)


DHL EXPRESS AND MANCHESTER UNITED BRING THE ‘THEATRE OF DREAMS’ TO THE WORLD’S MOST RURAL COMMUNITY OF RED DEVIL FANS

  • DHL Express’ “Delivering Dreams” campaign provides professional-grade, all-weather football pitch to the isolated community of Mae Suek, Thailand
  • Manchester United legend Patrice Evra was on hand to open the facility and led the first training session on the pitch with local children
  • Manchester United captain Bruno Fernandes sent an inspiring video message and provided club jerseys to the population who almost exclusively support the Red Devils
  • Over 1,000 children will now have access to training facilities every day and throughout the year, overcoming the extreme weather, geographic hurdles and mountainous terrain

LONDON, March 25, 2026 /PRNewswire/ — DHL Express has partnered with Manchester United to provide a professional-grade, all-weather football pitch to one of the most geographically isolated communities in the world – Mae Suek, Thailand – a region where over 85% of the population are lifelong supporters of the Red Devils.


DHL Express, the Official Logistics Partner of Manchester United, delivered a professional-grade, all-weather football pitch to Mae Suek, Thailand, for the ‘Delivering Dreams’ campaign. Find out more here: https://inmotion.dhl/en/staging/manchester-united/delivering-dreams

DHL Express, the official logistics partner of Manchester United since 2011, delivered the pitch alongside club legend Patrice Evra, who led the first training session on the new surface to inspire a generation of players in a region where the “Theatre of Dreams” had previously only existed on television screens.

Located 140km and more than four hours from the nearest major city, Chiang Mai, and a 2.5-hour round trip from the closest functional football pitch, Mae Suek is home to 11 villages and 11,577 people who share a love for the beautiful game and Manchester United in particular.

However, extreme weather conditions that frequently renders the local fields unusable, combined with a mountainous terrain that offers very little flat ground, has meant that Mae Suek has long struggled with a lack of safe sporting facilities, which sidelines the community’s passion for playing football.

So, as part of DHL Express’ “Delivering Dreams” campaign, the global logistic experts, together with Manchester United, surprised the community by providing high-quality infrastructure on Jericho Farm. The 9×9 pitch is made to world-class standards, featuring premium FIFA Grade 4G turf, similar to what is found at Manchester United’s Carrington training ground.

The new facility will ensure that over 1,000 students from two schools and three neighbouring villages can now access training facilities every day, regardless of the tropical climate, whilst also hosting regional tournaments throughout the year and applications for the Chiang Mai FC Academy.

Patrice Evra, Manchester United legend, said: “The ‘Delivering Dreams’ campaign with DHL Express is fantastic. When I saw the smiles on the kids’ faces when they played on this beautiful football pitch for the first time, it was a moment I won’t forget. When I was that age, I didn’t have the opportunity or the luxury to play on that kind of pitch. It’s an amazing campaign and an honour to be chosen to cut the cord and be the first one playing on the pitch with those kids.”

Mr V, owner of Jericho Farm, said: “It is a privilege to use my farm as the location for the region’s first ever football pitch which we can use all year round. We are a community of massive Manchester United fans, but until now, we didn’t always have the opportunity to play the game that everyone loves so much. I am excited knowing that everyone can now play sport whenever they choose, and it brings me great joy to see children having so much fun.”

Manchester United captain Bruno Fernandes also shared inspiring video messages and provided club jerseys, upon hearing from these avid fans, including Mr Som Chai, a referee for local grassroots clubs and his son, Man Yoo, who is named after his favourite team. Meanwhile, the president of the Khun Yuam Manchester United Supporters Club is nicknamed Aoddy Sherringham, celebrating his status as the area’s best ever football player.

Delivered by DHL Express Thailand, five trucks drove 500 miles from Bangkok to Jericho Farm – almost the length of the entire country – over the course of two days. The installation of the pitch required land clearing, soil excavation and site-levellling to prepare the land, while 12 members of the local tribe as part of the Hmong Tribal communities were on hand to bless the pitch upon completion.

Bruno Fernandes, Manchester United captain, said: “It is projects like this that inspire young children from around the world to believe that they can one day play at the Theatre of Dreams. The enjoyment and the passion to play football is the same, whether it is on your local pitch or in front of 75,000 fans at Old Trafford. It’s a great project and I know it will be enjoyed by the children and wider community of Mae Suek.”

Mason Mount, Manchester United player, said: “It’s an amazing project to be able to supply a pitch in such a remote area. It’s magical for the kids in that local area to see a pitch like that. To see that quality of pitch and how lucky we are to be able to play on such pitches, you want everyone to be able to experience something like that. I know a lot of the planning that has gone into it has been very difficult and taken a lot of time to sort everything out, but what an amazing story and for the kids it will be so special.”

Elliott Santon, Head of Global Sponsorships at DHL Express, said: “At DHL Express, we are always looking for opportunities to deliver on our mission to connect people and improve lives. It is a proud moment to work with our long-term partners at Manchester United to provide the people of Mae Suek, Thailand, with access to a professional grade football pitch. To hear the community’s love for the game and how playing sport will benefit the region for generations to come was very rewarding.”

The “Delivering Dreams” campaign brings to life DHL Express’ purpose mission of ‘Connecting People and Improving Lives’, by using football and our legacy partnership with Manchester United as a platform to unite communites for a better world.

Video – https://mma.prnasia.com/media2/2941414/DHL_Express.mp4

DHL Express, the Official Logistics Partner of Manchester United, delivered a professional-grade, all-weather football pitch to Mae Suek, Thailand, for the 'Delivering Dreams' campaign. Find out more here: https://inmotion.dhl/en/staging/manchester-united/delivering-dreams
DHL Express, the Official Logistics Partner of Manchester United, delivered a professional-grade, all-weather football pitch to Mae Suek, Thailand, for the ‘Delivering Dreams’ campaign. Find out more here: https://inmotion.dhl/en/staging/manchester-united/delivering-dreams

DouYu International Holdings Limited Reports Fourth Quarter and Full Year 2025 Unaudited Financial Results

WUHAN, China, March 25, 2026 /PRNewswire/ — DouYu International Holdings Limited (“DouYu” or the “Company”) (Nasdaq: DOYU), a leading game-centric live streaming platform in China and a pioneer in the eSports value chain, today announced its unaudited financial results for the fourth quarter and full year ended December 31, 2025.

Fourth Quarter 2025 Financial Highlights

  • Total net revenues in the fourth quarter of 2025 were RMB918.8 million (US$131.4 million), compared with RMB1,136.0 million in the same period of 2024.
  • Gross profit in the fourth quarter of 2025 was RMB118.0 million (US$16.9 million), compared with RMB69.8 million in the same period of 2024. 
  • Income from operations in the fourth quarter of 2025 was RMB4.7 million (US$0.7 million), compared with a loss from operations of RMB192.9 million in the same period of 2024.
  • Net income in the fourth quarter of 2025 was RMB1.4 million (US$0.2 million), compared with a net loss of RMB173.1 million in the same period of 2024.
  • Adjusted net income (non-GAAP)[1] in the fourth quarter of 2025 was RMB12.6 million (US$1.8 million), compared with an adjusted net loss (non-GAAP) of RMB78.2 million in the same period of 2024.

Full Year 2025 Financial Highlights

  • Total net revenues for the full year of 2025 were RMB3,818.9 million (US$546.1 million), compared with RMB4,270.8 million for the full year of 2024.
  • Gross profit for the full year of 2025 was RMB489.5 million (US$70.0 million), compared with RMB323.8 million for the full year of 2024. 
  • Net loss for the full year of 2025 was RMB29.1 million (US$4.2 million), compared with RMB306.8 million for the full year of 2024.
  • Adjusted net income (non-GAAP) for the full year of 2025 was RMB40.2 million (US$5.7 million), compared with an adjusted net loss (non-GAAP) of RMB249.2 million for the full year of 2024.

Ms. Simin Ren, Co-Chief Executive Officer of DouYu, commented, “Through the collective efforts of the entire DouYu team, we significantly improved our overall business performance in 2025 compared with 2024, despite a challenging external environment. Over the past year, we have made notable strides in diversifying our revenue and improving cost efficiency. Revenues from our innovative business, advertising and other sector grew 37% year over year, strengthening our competitive resilience and markedly enhancing financial sustainability. These accomplishments have laid a solid foundation for our long-term growth. In the fourth quarter, we remained focused on our core business and continued to enhance user experience. We refreshed our brand image and introduced our new slogan, ‘See Every Passion.’ We also resumed hosting in-person events with the Optics Valley ESports Carnival, attracting tens of millions of participants, both online and offline. Looking ahead, we will continue to place user passion at the center of our strategy, improve the quality of our content and services and drive ongoing innovation to create long-term value.”

Mr. Hao Cao, Vice President of DouYu, commented, “In the fourth quarter of 2025, amid continued pressure on our live streaming business, we sustained profitability and steady cash flow by focusing on operational efficiency. On a full-year basis, our financial capability saw substantial development. Gross margin reached 12.8% in 2025, a significant improvement from 7.6% in 2024. Adjusted net income turned positive at RMB40.2 million, compared with an adjusted net loss of RMB249.2 million in 2024. Our revenue diversification and cost-efficiency initiatives and optimized resource allocation have bolstered financial resilience, providing a stronger foundation for the Company to maintain robust operations and pursue healthy growth in a competitive environment.”

Fourth Quarter 2025 Operational Highlights

  • In the fourth quarter, average mobile MAUs[2] were 27.6 million, compared with 30.5 million in the third quarter of 2025, primarily attributable to the continued impact of cost structure optimization and a more disciplined content supply strategy, as well as the ongoing reduction of low-ROI events. These adjustments reduced retention and engagement among light users. Core users and paying users were relatively less affected, with the number of paying users remaining stable. We will continue to improve the user experience through innovations in activity design, monetization models and collaboration approaches to further enhance the efficiency and appeal of our events and content offerings. During the fourth quarter, we co-hosted tournaments and offline events and will continue to explore new formats for events and content going forward.
  • In the fourth quarter, the number of quarterly average paying users[3] for live streaming-related business was 2.6 million, with a quarterly ARPPU of RMB230. The slight decrease in paying users was primarily attributable to weaker consumer spending amid the prevailing macroeconomic environment as well as fewer promotional activities resulting from adjustments to our platform’s operational strategy.
  • In the fourth quarter, revenues from our voice-based social networking business reached RMB271.0 million. Average MAUs for the voice-based social networking business for the fourth quarter were 286,300, with 63,600 monthly average paying users[4]. During the quarter, we focused on optimizing the traffic distribution mechanism and resource allocation efficiency for the voice business. These efforts enhanced the business’ profitability while maintaining a healthy community ecosystem, delivering performance in line with our expectations.

Fourth Quarter 2025 Financial Results

Total net revenues in the fourth quarter of 2025 decreased by 19.1% to RMB918.8 million (US$131.4 million), compared with RMB1,136.0 million in the same period of 2024.

Livestreaming revenues in the fourth quarter of 2025 decreased by 29.8% to RMB513.0 million (US$73.4 million) from RMB730.9 million in the same period of 2024, primarily driven by the decrease in both the number of total paying users and average revenue per paying user as a result of fewer promotional activities and reduced consumer spending amid the prevailing macroeconomic environment.

Innovative business, advertising and other revenues in the fourth quarter of 2025 increased by 0.2% to RMB405.8 million (US$58.0 million) from RMB405.1 million in the same period of 2024, primarily attributable to increased revenues from our voice-based social networking service and seasonal fluctuations in gaming membership revenues.

Cost of revenues in the fourth quarter of 2025 decreased by 24.9% to RMB800.8 million (US$114.5 million) from RMB1,066.2 million in the same period of 2024.

Revenue-sharing fees and content costs in the fourth quarter of 2025 decreased by 25.3% to RMB669.6 million (US$95.7 million) from RMB896.2 million in the same period of 2024, primarily driven by reductions in content costs as part of our cost optimization efforts, as well as lower revenue-sharing fees resulting from decreased live streaming revenues.

Bandwidth costs in the fourth quarter of 2025 decreased by 32.2% to RMB47.7 million (US$6.8 million) from RMB70.3 million in the same period of 2024, primarily attributable to improved bandwidth allocation and a year-over-year decrease in peak bandwidth usage.

Gross profit in the fourth quarter of 2025 increased by 69.1% to RMB118.0 million (US$16.9 million) from RMB69.8 million in the same period of 2024, primarily driven by lower content and bandwidth costs. Gross margin in the fourth quarter of 2025 increased to 12.8% from 6.1% in the same period of 2024.

Sales and marketing expenses in the fourth quarter of 2025 decreased by 40.0% to RMB47.6 million (US$6.8 million) from RMB79.3 million in the same period of 2024, primarily attributable to lower promotional expenses and reduced staff-related expenses.

Research and development expenses in the fourth quarter of 2025 decreased by 1.0% to RMB33.8 million (US$4.8 million) from RMB34.2 million in the same period of 2024, primarily attributable to lower staff-related expenses.

General and administrative expenses in the fourth quarter of 2025 decreased by 62.6% to RMB26.8 million (US$3.8 million) from RMB71.7 million in the same period of 2024, primarily attributable to the absence of one-off employee-streamlining expenses incurred in the same period last year and lower staff-related expenses.

Income from operations in the fourth quarter of 2025 was RMB4.7 million (US$0.7 million), compared with a loss from operations of RMB192.9 million in the same period of 2024.

Net income in the fourth quarter of 2025 was RMB1.4 million (US$0.2 million), compared with a net loss of RMB173.1 million in the same period of 2024.

Adjusted net income (non-GAAP), which is calculated as net income excluding share of loss in equity method investments and impairment losses and fair value adjustments on investments, was RMB12.6 million (US$1.8 million) in the fourth quarter of 2025, compared with an adjusted net loss (non-GAAP) of RMB78.2 million in the same period of 2024.

Basic and diluted net income per ADS[5] in the fourth quarter of 2025 were both RMB0.05 (US$0.01).

Adjusted basic and diluted net income per ADS (non-GAAP) in the fourth quarter of 2025 were both RMB0.42 (US$0.06).

Full Year 2025 Financial Results

Total net revenues for the full year of 2025 were RMB3,818.9 million (US$546.1 million), compared with RMB4,270.8 million in the same period of 2024, primarily driven by the year-over-year decrease in live streaming revenues, which was partially offset by the increase in innovative business, advertising and other revenues.

Gross profit for the full year of 2025 was RMB489.5 million (US$70.0 million), compared with RMB323.8 million in the same period of 2024.

Adjusted net income (non-GAAP), which is calculated as net income excluding share of loss in equity method investments and impairment losses and fair value adjustments on investments, was RMB40.2 million (US$5.7 million) for the full year of 2025, compared with an adjusted net loss (non-GAAP) of RMB249.2 million in the same period of 2024.

Basic and diluted net loss per ADS for the full year of 2025 were both RMB0.96 (US$0.14).

Adjusted basic and diluted net income per ADS (non-GAAP) for the full year of 2025 were both RMB1.33 (US$0.19).

Cash and cash equivalents, restricted cash and bank deposits

As of December 31, 2025, the Company had cash and cash equivalents, restricted cash, restricted cash in other non-current assets, and short-term and long-term bank deposits of RMB2,283.7 million (US$326.6 million), compared with RMB4,467.8 million as of December 31, 2024. The decrease was primarily attributable to a special cash dividend of US$300 million.

[1] “Adjusted net income (non-GAAP)” is defined as net income excluding share of loss (income) in equity method investments and impairment losses and fair value adjustments on investments. For more information, please refer to “Use of Non-GAAP Financial Measures” and “Reconciliations of GAAP and Non-GAAP Results” at the end of this press release.

[2] “MAUs” refers to the number of active mobile users (exclusive of innovative business unless the context otherwise indicates) in a given period. Average mobile MAUs for a given period is calculated by dividing (i) the sum of active mobile users for each month of such period, by (ii) the number of months in such period.

[3] “Quarterly average paying users” refers to the average paying users for each quarter during a given period of time calculated by dividing (i) the sum of paying users for each quarter of such period, by (ii) the number of quarters in such period. “Paying user” refers to a registered user that has purchased virtual gifts on our platform at least once during the relevant period.

[4] “Monthly average paying users” refers to the monthly average number of paying users during a given period of time calculated by dividing (i) the sum of paying users in each month of such period, by (ii) the number of months in such period. “Paying user” refers to a registered user that has purchased virtual gifts on our platform at least once during the relevant period.

[5] Each ADS represents one ordinary share for the relevant period and calendar year.

About DouYu International Holdings Limited

Headquartered in Wuhan, China, DouYu International Holdings Limited (Nasdaq: DOYU) is a leading game-centric live streaming platform in China and a pioneer in the eSports value chain. DouYu operates its platform on both PC and mobile apps to bring users access to immersive and interactive games and entertainment live streaming, a wide array of video and graphic content, as well as opportunities to participate in community events and discussions. By nurturing a sustainable technology-based talent development system and relentlessly producing high-quality content, DouYu consistently delivers premium content through the integration of live streaming, video, graphics, and virtual communities with a primary focus on games. This enables DouYu to continuously enhance its user experience and pursue long-term healthy development. For more information, please see http://ir.douyu.com.

Use of Non-GAAP Financial Measures

Adjusted (loss) income from operations is calculated as (loss) income from operations adjusted for Impairment of goodwill and intangible assets. Adjusted net (loss) income is calculated as net (loss) income adjusted for share of (income) loss in equity method investments, impairment losses and fair value adjustments on investments, and impairment losses of intangible assets. Adjusted net (loss) income attributable to DouYu is calculated as net (loss) income attributable to DouYu adjusted for share of (income) loss in equity method investments, impairment losses and fair value adjustments on investments, and impairment losses of intangible assets. Adjusted basic and diluted net (loss) income per ordinary share is non-GAAP net (loss) income attributable to ordinary shareholders divided by the weighted average number of ordinary shares used in the calculation of non-GAAP basic and diluted net (loss) income per ordinary share. The Company adjusted the impact of (i) share of (income) loss in equity method investments, (ii) impairment losses and fair value adjustments on investments, and (iii) Impairment losses of intangible assets to understand and evaluate the Company’s core operating performance. The non-GAAP financial measures are presented to enhance investors’ overall understanding of the Company’s financial performance and should not be considered a substitute for, or superior to, the financial information prepared and presented in accordance with U.S. GAAP. Investors are encouraged to review the reconciliation of the historical non-GAAP financial measures to their most directly comparable GAAP financial measures. As non-GAAP financial measures have material limitations as analytical metrics and may not be calculated in the same manner by all companies, they may not be comparable to other similarly titled measures used by other companies. In light of the foregoing limitations, you should not consider non-GAAP financial measures as a substitute for, or superior to, such metrics in accordance with U.S. GAAP.

For more information on these non-GAAP financial measures, please see the table captioned “Reconciliations of GAAP and Non-GAAP Results” near the end of this release.

Exchange Rate Information

This announcement contains translations of certain RMB amounts into U.S. dollars at a specified rate solely for the convenience of the reader. Unless otherwise noted, all translations from RMB to U.S. dollars are made at a rate of RMB6.9931 to US$1.00, the noon buying rate in effect on December 31, 2025, in the H.10 statistical release of the Federal Reserve Board. The Company makes no representation that the RMB amounts could have been, or could be, converted, realized, or settled in U.S. dollars, at that rate on December 31, 2025, or at any other rate.

Safe Harbor Statement

This press release contains forward-looking statements. These statements are made under the “safe harbor” provisions of the U.S. Private Securities Litigation Reform Act of 1995. Statements that are not historical facts, including statements about the Company’s beliefs and expectations, are forward-looking statements. Forward-looking statements involve inherent risks and uncertainties, and a number of factors could cause actual results to differ materially from those contained in any forward-looking statement, including but not limited to the following: the Company’s results of operations and financial condition; the Company’s business strategies and plans; general market conditions, in particular, the game live streaming market; the ability of the Company to retain and grow active and paying users; changes in general economic and business conditions in China; any adverse changes in laws, regulations, rules, policies or guidelines applicable to the Company; and assumptions underlying or related to any of the foregoing. In some cases, forward-looking statements can be identified by words or phrases such as “may,” “will,” “expect,” “anticipate,” “target,” “aim,” “estimate,” “intend,” “plan,” “believe,” “potential,” “continue,” “is/are likely to” or other similar expressions. Further information regarding these and other risks, uncertainties or factors is included in the Company’s filings with the U.S. Securities and Exchange Commission. The announced results of the fourth quarter and full year of 2025 are preliminary and unaudited. All information provided in this press release is as of the date of this press release, and the Company does not undertake any duty to update such information, except as required under applicable law.

Investor Relations Contact

In China:

Chenyang Yan

DouYu International Holdings Limited

Email: ir@douyu.tv

Tel: +86 (10) 6508-0677


Andrea Guo

Piacente Financial Communications

Email: douyu@tpg-ir.com

Tel: +86 (10) 6508-0677


In the United States:

Brandi Piacente

Piacente Financial Communications

Email: douyu@tpg-ir.com

Tel: +1-212-481-2050


UNAUDITED CONDENSED CONSOLIDATED BALANCE SHEETS

(All amounts in thousands, except share, ADS, per share and per ADS data)

As of December 31

As of December 31

2024

2025

2025

ASSETS

RMB

RMB

US$ (1)

Current assets:

Cash and cash equivalents

1,017,148

1,759,127

251,552

Restricted cash

83

35

5

Short-term bank deposits

3,070,374

502,502

71,857

Accounts receivable, net

49,057

77,584

11,094

Prepayments

26,885

15,790

2,258

Amounts due from related parties

74,175

91,601

13,099

Other current assets, net

231,354

185,264

26,492

Total current assets

4,469,076

2,631,903

376,357

Property and equipment, net

7,093

5,040

721

Intangible assets, net

60,917

33,580

4,802

Long-term bank deposits

360,000

–

–

Investments

456,815

383,683

54,866

Right-of-use assets, net

15,816

7,900

1,130

Other non-current assets

76,616

57,845

8,272

Total non-current assets

977,257

488,048

69,791

TOTAL ASSETS

5,446,333

3,119,951

446,148


LIABILITIES AND SHAREHOLDERS’ EQUITY

LIABILITIES

Current liabilities:

Accounts payable

498,667

554,131

79,240

Advances from customers

4,444

2,311

330

Deferred revenue

252,346

236,900

33,876

Accrued expenses and other current liabilities

242,517

218,921

31,305

Amounts due to related parties

222,589

112,307

16,060

Lease liabilities due within one year

11,458

6,703

959

Total current liabilities

1,232,021

1,131,273

161,770

Lease liabilities

4,223

1,306

187

Total non-current liabilities

4,223

1,306

187

TOTAL LIABILITIES

1,236,244

1,132,579

161,957

(1) Translations of certain RMB amounts into U.S. dollars at a specified rate are solely for the convenience of the reader. Unless otherwise noted,
all translations from RMB to U.S. dollars are made at a rate of RMB6.9931 to US$1.00, the noon buying rate in effect on December 31, 2025, in
the H.10 statistical release of the Federal Reserve Board.


UNAUDITED CONDENSED CONSOLIDATED BALANCE SHEETS (CONTINUED)

(All amounts in thousands, except share, ADS, per share and per ADS data)

As of December 31

As of December 31

2024

2025

2025

RMB

RMB

US$ (1)

SHAREHOLDERS’ EQUITY

Ordinary shares

20

20

3

Additional paid-in capital

7,514,498

5,363,717

767,001

Accumulated deficit

(3,791,817)

(3,820,899)

(546,381)

Accumulated other comprehensive income

487,388

444,534

63,568

Total DouYu Shareholders’ Equity

4,210,089

1,987,372

284,191

Total Shareholders’ Equity

4,210,089

1,987,372

284,191

TOTAL LIABILITIES AND SHAREHOLDERS’ EQUITY

5,446,333

3,119,951

446,148

(1) Translations of certain RMB amounts into U.S. dollars at a specified rate are solely for the convenience of the reader. Unless otherwise noted,
all translations from RMB to U.S. dollars are made at a rate of RMB6.9931 to US$1.00, the noon buying rate in effect on December 31, 2025, in
the H.10 statistical release of the Federal Reserve Board.


UNAUDITED CONDENSED CONSOLIDATED STATEMENTS OF INCOME (LOSS)

(All amounts in thousands, except share, ADS, per share and per ADS data)

Three Months Ended

Year Ended

Dec 31,

2024

Sep 30,

2025

Dec 31,

2025

Dec 31,

2025

Dec 31,

2024

Dec 31,

2025

Dec 31,

2025

RMB

RMB

RMB

US$ (1)

RMB

RMB

US$ (1)

Net revenues

1,136,000

899,111

918,775

131,383

4,270,825

3,818,852

546,088

Cost of revenues

(1,066,209)

(783,022)

(800,785)

(114,511)

(3,946,993)

(3,329,325)

(476,087)

Gross profit

69,791

116,089

117,990

16,872

323,832

489,527

70,001

Operating (expenses) income(2)

Sales and marketing expenses

(79,348)

(52,331)

(47,637)

(6,812)

(311,140)

(234,482)

(33,530)

General and administrative expenses

(71,674)

(35,274)

(26,780)

(3,829)

(204,429)

(137,657)

(19,685)

Research and development expenses

(34,150)

(26,888)

(33,810)

(4,835)

(181,676)

(121,058)

(17,311)

Other operating (expenses) income, net

(77,520)

10,334

(5,041)

(721)

(200,174)

8,427

1,205

Total operating expenses

(262,692)

(104,159)

(113,268)

(16,197)

(897,419)

(484,770)

(69,321)

(Loss) Income from operations

(192,901)

11,930

4,722

675

(573,587)

4,757

680

Other (expenses) income, net

(21,401)

(10,124)

(8,100)

(1,158)

21,898

(67,315)

(9,626)

Interest income, net

45,147

18,105

16,884

2,414

263,052

64,330

9,199

Foreign exchange income (expenses), net

546

(232)

(526)

(75)

1,235

(517)

(74)

(Loss) income before income taxes and share of

 income (loss) in equity method investments


(168,609)

19,679

12,980

1,856

(287,402)

1,255

179

Income tax expense

(6,464)

(6,662)

(8,463)

(1,210)

(15,407)

(28,409)

(4,062)

Share of income (loss) in equity method investments

1,981

(1,688)

(3,146)

(450)

(4,001)

(1,928)

(276)

Net (loss) income

(173,092)

11,329

1,371

196

(306,810)

(29,082)

(4,159)

Net (loss) income attributable to ordinary 

    shareholders of the Company


(173,092)

11,329

1,371

196

(306,810)

(29,082)

(4,159)

Net (loss) income per ordinary share

Basic

(5.74)

0.38

0.05

0.01

(9.95)

(0.96)

(0.14)

Diluted

(5.74)

0.38

0.05

0.01

(9.95)

(0.96)

(0.14)

Net (loss) income per ADS(3)

Basic

(5.74)

0.38

0.05

0.01

(9.95)

(0.96)

(0.14)

Diluted

(5.74)

0.38

0.05

0.01

(9.95)

(0.96)

(0.14)

Weighted average number of ordinary shares used in calculating net (loss) income per ordinary share

Basic

30,178,859

30,178,859

30,178,859

30,178,859

30,832,271

30,178,859

30,178,859

Diluted

30,178,859

30,178,859

30,178,859

30,178,859

30,832,271

30,178,859

30,178,859

Weighted average number of ADS used in calculating net (loss) income per ADS(3)

Basic

30,178,859

30,178,859

30,178,859

30,178,859

30,832,271

30,178,859

30,178,859

Diluted

30,178,859

30,178,859

30,178,859

30,178,859

30,832,271

30,178,859

30,178,859

(1) Translations of certain RMB amounts into U.S. dollars at a specified rate are solely for the convenience of the reader. Unless otherwise noted, all translations
from RMB to U.S. dollars are made at a rate of RMB6.9931 to US$1.00, the noon buying rate in effect on December 31, 2025, in the H.10 statistical release
of the Federal Reserve Board.

(2) Every one ADS represents one ordinary share.


RECONCILIATIONS OF GAAP AND NON-GAAP RESULTS

(All amounts in thousands, except share, ADS, per share and per ADS data)

Three Months Ended

Year Ended

Dec 31,

2024

Sep 30,

2025

Dec 31,

2025

Dec 31,

2025

Dec 31,

2024

Dec 31,

2025

Dec 31,

2025

RMB

RMB

RMB

US$ (1)

RMB

RMB

US$ (1)

(Loss) Income from operations

(192,901)

11,930

4,722

675

(573,587)

4,757

680

Add:

Impairment losses of intangible assets

75,473

–

–

–

75,473

–

–

Adjusted Operating (loss) income (non-GAAP)

(117,428)

11,930

4,722

675

(498,114)

4,757

680

Net (loss) income

(173,092)

11,329

1,371

196

(306,810)

(29,082)

(4,159)

Add:

Share of (income) loss in equity method investments

(1,981)

1,688

3,146

450

4,001

1,928

276

Impairment losses and fair value adjustments on
investments(2)

21,401

10,124

8,100

1,158

(21,898)

67,315

9,626

Impairment losses of intangible assets

75,473

–

–

–

75,473

–

–

Adjusted net (loss) income (non-GAAP)

(78,199)

23,141

12,617

1,804

(249,234)

40,161

5,743

Net (loss) income attributable to DouYu

(173,092)

11,329

1,371

196

(306,810)

(29,082)

(4,159)

Add:

Share of (income) loss in equity method investments

(1,981)

1,688

3,146

450

4,001

1,928

276

Impairment losses and fair value adjustments on
investments

21,401

10,124

8,100

1,158

(21,898)

67,315

9,626

Impairment losses of intangible assets

75,473

–

–

–

75,473

–

–

Adjusted net (loss) income attributable to DouYu

(78,199)

23,141

12,617

1,804

(249,234)

40,161

5,743

Adjusted net (loss) income per ordinary share

 (non-GAAP)

Basic

(2.59)

0.77

0.42

0.06

(8.08)

1.33

0.19

Diluted

(2.59)

0.77

0.42

0.06

(8.08)

1.33

0.19

Adjusted net (loss) income per ADS(2) (non-GAAP)


Basic

(2.59)

0.77

0.42

0.06

(8.08)

1.33

0.19

Diluted

(2.59)

0.77

0.42

0.06

(8.08)

1.33

0.19

Weighted average number of ordinary shares used in calculating Adjusted net (loss) income per ordinary share

Basic

30,178,859

30,178,859

30,178,859

30,178,859

30,832,271

30,178,859

30,178,859

Diluted

30,178,859

30,178,859

30,178,859

30,178,859

30,832,271

30,178,859

30,178,859

Weighted average number of ADS used in calculating net (loss) income per ADS(3)

Basic

30,178,859

30,178,859

30,178,859

30,178,859

30,832,271

30,178,859

30,178,859

Diluted

30,178,859

30,178,859

30,178,859

30,178,859

30,832,271

30,178,859

30,178,859

(1) Translations of certain RMB amounts into U.S. dollars at a specified rate are solely for the convenience of the reader. Unless otherwise noted, all translations
from RMB to U.S. dollars are made at a rate of RMB6.9931 to US$1.00, the noon buying rate in effect on December 31, 2025, in the H.10 statistical release
of the Federal Reserve Board.

(2) Impairment losses and fair value adjustments on investments was included in line item “Other income (expenses), net” of condensed consolidated
statements of income (loss).    

(3) Every one ADS represents one ordinary share.


Kuaishou Technology Announces Fourth Quarter and Full Year 2025 Financial Results

HONG KONG, March 25, 2026 /PRNewswire/ — Kuaishou Technology (“Kuaishou” or the “Company”; HKD Counter Stock Code: 01024 / RMB Counter Stock Code: 81024), a leading content community and social platform, today announced its financial results for the fourth quarter and full fiscal year ended December 31, 2025.

Fourth Quarter 2025 Key Highlights

  • Average DAUs on Kuaishou APP were 407.7 million, representing an increase of 1.7% from 401.0 million for the same period of 2024.
  • Average MAUs on Kuaishou APP were 740.7 million, representing an increase of 0.7% from 735.6 million for the same period of 2024.
  • Total e-commerce GMV(1) was RMB521.8 billion, representing an increase of 12.9% from RMB462.1 billion for the same period of 2024.
  • Total revenues increased by 11.8% to RMB39.6 billion from RMB35.4 billion for the same period of 2024. Online marketing services and live streaming contributed 59.7% and 24.4%, respectively, to the total revenues. The other 15.9% came from other services.
  • Gross profit increased by 14.1% to RMB21.8 billion from RMB19.1 billion for the same period of 2024. Gross profit margin improved to 55.1%, from 54.0% for the same period of 2024.
  • Profit for the period increased to RMB5.2 billion, from RMB4.0 billion for the same period of 2024. Adjusted net profit(2) increased to RMB5.5 billion from RMB4.7 billion for the same period of 2024.
  • Operating profit from the domestic segment(3) increased to RMB6.1 billion from RMB4.4 billion for the same period of 2024. Operating loss from the overseas segment(3) was RMB59 million, compared to RMB236 million for the same period of 2024.

Full Year 2025 Key Highlights

  • Average DAUs on Kuaishou APP were 410.2 million, representing an increase of 2.7% from 399.4 million in 2024.
  • Average MAUs on Kuaishou APP were 724.6 million, representing an increase of 2.1% from 709.7 million in 2024.
  • Total e-commerce GMV(1) was RMB1,598.1 billion, representing an increase of 15.0% from RMB1,389.6 billion in 2024.
  • Total revenues increased by 12.5% to RMB142.8 billion from RMB126.9 billion in 2024. Online marketing services and live streaming contributed 57.1% and 27.4%, respectively, to the total revenues. The other 15.5% came from other services.
  • Gross profit increased by 13.4% to RMB78.5 billion from RMB69.3 billion in 2024. Gross profit margin improved to 55.0%, from 54.6% in 2024.
  • Profit for the year increased to RMB18.6 billion, from RMB15.3 billion in 2024. Adjusted net profit(2) increased to RMB20.6 billion from RMB17.7 billion in 2024.
  • Operating profit from the domestic segment(3) increased to RMB21.2 billion from RMB16.4 billion in 2024. Operating loss from the overseas segment(3) was RMB76 million, compared to RMB934 million in 2024.
  • During the twelve months ended December 31, 2025, the Company repurchased approximately 56.78 million shares on the Hong Kong Stock Exchange for a consideration of approximately HKD3.12 billion.

Mr. Cheng Yixiao, Co-founder, Chairman, and Chief Executive Officer of Kuaishou, commented, “In 2025, guided by our technology-driven, user-centric approach, we accelerated the execution of our AI strategy, leveraging cutting-edge AI capabilities to fuel upgrades and vitality across Kuaishou’s content and commercial ecosystems. This strategic momentum not only delivered incremental value to our users and partners but also underpinned a year of solid operational and financial performance. For the full year of 2025, our average DAUs reached 410 million, and total revenues increased by 12.5% year-over-year to RMB142.8 billion. Adjusted net profit for the full year increased by 16.5% year-over-year to RMB20.6 billion, with a 14.5% adjusted net margin. We remain committed to investing in AI technology and have made remarkable progress. Our multimodal large video generation model, Kling AI, accelerated its iteration throughout 2025, achieving breakthroughs in model capabilities, product experience and monetization potential, while fortifying its global leadership in AI video generation. Moving forward, we will remain deeply attuned to users’ evolving needs, further accelerating the integration of AI and innovative applications across all business scenarios, unlocking greater values to our users, business partners, and shareholders.”

Fourth Quarter 2025 Financial Review

Revenue from our online marketing services increased by 14.5% to RMB23.6 billion for the fourth quarter of 2025, from RMB20.6 billion for the same period of 2024, primarily attributable to the accelerated integration and innovative application of AI across diverse online marketing services scenarios.

Revenue from our live streaming business was RMB9.7 billion and RMB9.8 billion for the fourth quarter of 2025 and 2024, respectively.

Revenue from our other services increased by 28.0% to RMB6.3 billion for the fourth quarter of 2025, from RMB4.9 billion for the same period of 2024, primarily due to the growth of our e-commerce business and Kling AI business. The growth of e-commerce business was represented by the growth in our e-commerce GMV. The growth of Kling AI business was primarily attributable to our advanced AI technology and exceptional product performance.

Other Key Financial Information for the Fourth Quarter of 2025

Operating profit was RMB5.8 billion, increasing from RMB4.3 billion for the same period of 2024.

Adjusted EBITDA(4) was RMB8.0 billion, increasing from RMB6.9 billion for the same period of 2024.

Full Year 2025 Financial Review

Revenue from our online marketing services increased by 12.5% to RMB81.5 billion in 2025 from RMB72.4 billion in 2024, primarily attributable to the accelerated integration and innovative application of AI across diverse online marketing services scenarios.

Revenue from our live streaming business increased by 5.5% to RMB39.1 billion in 2025 from RMB37.1 billion in 2024, as a result of our continuous efforts to develop a rich and healthy living streaming ecosystem and diverse high-quality content.

Revenue from our other services increased by 27.6% to RMB22.2 billion in 2025 from RMB17.4 billion in 2024, primarily attributable to the growth of our e-commerce business and Kling AI business. The growth of e-commerce business was represented by the growth in our e-commerce GMV. The growth of Kling AI business was primarily attributable to our advanced AI technology and exceptional product performance.

Other Key Financial Information for the Full Year of 2025

Operating profit was RMB20.6 billion, increasing from RMB15.3 billion in 2024.

Adjusted EBITDA(4) was RM29.8 billion, increasing from RMB24.8 billion in 2024.

Total available funds(5) reached RMB104.9 billion as of December 31, 2025.

Notes:

(1) Placed on or directed to our partners through our platform.
(2) We define “adjusted net profit” as profit for the year or period adjusted by share-based compensation expenses and net fair value changes on investments.
(3) Unallocated items, which consist of share-based compensation expenses, other income, and other gains, net, are not included.
(4) We define “adjusted EBITDA” as adjusted net profit for the year or period adjusted by income tax expenses, depreciation of property and equipment, depreciation of right-of-use assets, amortization of intangible assets, and finance expense/(income), net.
(5) Total available funds which we considered in cash management included but not limited to cash and cash equivalents, time deposits, financial assets and restricted cash. Financial assets mainly included wealth management products and others.

Business Review

In the year of 2025, guided by our “technology-driven, user-centric” philosophy, we accelerated the execution of our AI strategy across all major business scenarios. Our multimodal large video generation models Kling AI (可靈AI) maintained a globally leading position, and we continued to leverage our advanced AI capabilities to empower Kuaishou’s content and commercial ecosystems, driving high-quality growth across user scale, revenue and profitability.

In the fourth quarter of 2025, average DAUs on the Kuaishou App reached 407.7 million, demonstrating robust year-over-year growth. Total revenues increased by 11.8% year-over-year to RMB39.6 billion. Revenues from our core commercial business, including online marketing services and other services, primarily e-commerce, increased by 17.1% year-over-year. Adjusted net profit reached RMB5.5 billion in the fourth quarter of 2025. For the full year of 2025, average DAUs on the Kuaishou App reached 410.2 million, and total revenues increased by 12.5% year-over-year to RMB142.8 billion. Adjusted net profit for the full year increased by 16.5% year-over-year to RMB20.6 billion, with an adjusted net margin of 14.5%. As we expanded our AI investments, we continued to deliver steady improvements in the Group’s overall profitability. Our AI capabilities have become a core engine driving Kuaishou’s long-term growth.

AI business 

Kling AI (可靈AI) remained committed to its vision of empowering everyone to craft captivating stories with AI, aiming to become the premier, inclusive and efficient video-creation infrastructure for the AI era while driving continuous breakthroughs in model capabilities, product experience, and monetization. In the fourth quarter of 2025, Kling AI (可靈AI) accelerated the rollout of multiple model upgrades across several iterations. We launched Kling O1, the world’s first unified multimodal video model that integrated multimodal text, video, image and subject inputs, consolidating all generation and editing tasks into a single, all-encompassing engine. Kling O1’s unified architecture enables end-to-end content creation within one model system, allowing users to transition from generation to editing and refinement without switching tools. We also released the Kling 2.6 model, which incorporates “simultaneous audio-visual generation” capabilities. The model can generate a complete video containing natural voiceovers, action sound effects, and ambient audio in a single process. Kling 2.6 also introduced a motion control feature that enables users to replicate specific movements from uploaded videos or from the online motion library. By pairing this with a character reference image, users can generate character-specific videos with frame-level precision in both body movements and facial expressions.

In February 2026, we launched the Kling AI (可靈AI) 3.0 model series. Developed under an All-in-One product framework, Kling 3.0 model series supports full multimodal input and output, spanning text, images, audio and video, seamlessly integrating video understanding, generation and editing within a single, streamlined AI workflow. The models unify multiple tasks, including text-to-video, image-to-video and in-video editing, within a native multimodal architecture, enabling adherence to complex narrative logic, automated storyboarding and precise shot-level control while maintaining strong prompt adherence. 

Kling AI (可靈AI)‘s innovations in foundational models and product features have paved the way for widespread commercial applications across professional creative sectors, including marketing, e-commerce, film and television, short plays, animation and gaming. These capabilities have supported stronger adoption among professional creators and enterprise clients globally, accelerating its monetization. In the fourth quarter of 2025, Kling AI (可靈AI) achieved revenue of RMB340 million. Notably, in December 2025, Kling AI (可靈AI)‘s monthly revenue exceeded USD20 million, implying an Annualized Revenue Run Rate (ARR) of USD240 million. At the same time, Kling AI (可靈AI)‘s motion control feature gained significant traction across major global social media platforms, driving widespread discussion and distribution. This momentum broadened Kling AI (可靈AI)‘s reach beyond professional creators to a broader mainstream user base.

In the fourth quarter of 2025, we continued to deepen the impact of large AI models to empower our content and commercial ecosystems while driving further quality and efficiency improvements throughout our organizational infrastructure. In terms of strengthening the foundation of our content ecosystem, we independently developed and open-sourced the multimodal large language model Keye-671B model, which has demonstrated strong capabilities in video comprehension. Meanwhile, we upgraded our short-video and livestreaming content understanding system and launched TagNex, our next-generation tagging system, which enables more accurate content understanding, leading to increased users’ usage time and higher retention rates. In content recommendation, we iterated our end-to-end generative recommendation large model with the launch of OneRec-V2, continuously improving recommendation accuracy. For online marketing services, we further optimized our end-to-end generative recommendation technology. By deeply integrating multi-dimensional business data, we enhanced model performance and improved the precision of online marketing material recommendations. For intelligent bidding technology, we developed a bidding large model built on multi-scenario and multi-objective data. Together, our generative recommendation large models and intelligent bidding models drove roughly 5% growth in domestic online marketing services revenue in the fourth quarter of 2025. While reducing the cost of generating online marketing materials, AIGC technology also unlocked additional budgets from our marketing clients. In the fourth quarter of 2025, the total spending from online marketing services driven by AIGC marketing materials reached RMB4.0 billion.

For e-commerce business scenarios, during the fourth quarter of 2025, we further iterated our end-to-end generative retrieval architecture OneSearch. We introduced editable structured Semantic Identifier tailored to the e-commerce business, enhancing semantic understanding for mid-to-long-tail search queries. This drove a nearly 3% increase in search order volume in shopping mall for the fourth quarter of 2025. In addition, we expanded the applications of end-to-end generative recommendation technology from pan-shelf-based e-commerce scenarios to content-driven scenarios such as livestreaming rooms and short videos, propelling GMV growth in all e-commerce scenarios. For live streaming business scenarios, we further refined the AI Universe (AI萬象) gift customization feature to deliver greater interactivity, more dynamic presentations, and improved visual aesthetics, significantly increasing users’ willingness to send virtual gifts. In terms of organizational efficiency improvement, our proprietary AI coding tool CodeFlicker has become a core intelligent development tool for R&D engineers in their daily work. Currently, over 40% of Kuaishou’s new codes is generated by CodeFlicker.

Our AI businesses advancement is underpinned by our sustained investment and in-depth optimization in computing infrastructure. We have established a self-built data center in Ulanqab, Inner Mongolia, and are progressing steadily with the construction of a new computer center, which will further enhance the operational efficiency of our servers and bandwidth.

User and content ecosystem

In the fourth quarter of 2025, average DAUs on the Kuaishou App reached 407.7 million and MAUs reached 740.7 million, while the average daily time spent per DAU on the Kuaishou App was 126.0 minutes. We are committed to building a vibrant community with distinctive Kuaishou characteristics, continuously strengthening high-quality user growth, differentiated premium content supply, traffic mechanism optimization and interactive scenario development to achieve healthy, sustainable expansion in both user base and platform traffic. To drive high-quality user growth, we refined user acquisition strategies across channels to continually optimize user segments and improve retention rates. We also leveraged AI technology to enhance push strategies, leading to a higher user open rate for the Kuaishou App. In addition, we introduced innovative user retention initiatives that significantly improved ROI.

Harnessing our established capabilities in content operations, we supported the growth of benchmark creators like Xinyu the Ostrich Lady (心雨鴕鳥) and continued to cultivate high-quality content IPs with distinctive Kuaishou characteristics. Rural cultural and entertainment activities, exemplified by the Village Gateway Mini Stage (村口小舞台) empowered rural residents to move from viewers to active on-stage participants, featuring diverse content ranging from intangible cultural heritage performances to agricultural technology demonstrations. These initiatives not only enriched rural cultural life but also provided a new channel for promoting rural culture. We hosted the 6th Anniversary Concert for Teens in Times (時代少年團), which garnered over 680 million live streamings views. Leveraging live streaming, interactive features and AI-powered creative content, we crafted a shared youthful memory that fosters a mutual bond between the fans and idols.

We optimized our traffic mix to increase traffic exposure for top-tier original content, fostering a virtuous cycle between content creation and consumption. In the fourth quarter of 2025, the number of high-quality content uploads increased by more than 15% year-over-year. To further develop engagement scenarios, we continued to innovate private messaging engagement features, driving a year-over-year increase of nearly 3 percentage points in the daily average penetration rate of private messages among users with mutual followers during the fourth quarter of 2025.

Online marketing services

In the fourth quarter of 2025, revenue from online marketing services reached RMB23.6 billion, up 14.5% year-over-year. The accelerated integration and innovative application of AI across diverse online marketing services scenarios not only empowered our ecosystem partners but also created new growth momentum for our online marketing services business.

In the fourth quarter of 2025, within the lifestyle service sector, where clients primarily operate on a lead-based model, we helped clients reach users more efficiently and achieve higher user conversion rates by upgrading our private messaging products and optimizing our algorithms. At the same time, through continued expansion into more industries and client acquisition, we broadened our online marketing client base, driving incremental marketing placements. In addition, as lifestyle service-sector clients are predominantly small and medium-sized merchants, we leveraged AIGC tools to enhance their ability to produce marketing materials, driving further growth in online marketing spending.

In the fourth quarter of 2025, the content consumption sector, led by short plays, comic-style short plays and mini-games, along with the AI application sector, was a key revenue driver for our online marketing services. In the content consumption sector, short plays maintained solid growth momentum. By optimizing marketing materials exposure formats, we increased marketing spending in the short-play vertical. Meanwhile, with deep empowerment of AI technologies, comic-style short plays advanced rapidly. Through comprehensive support programs and the rollout of a comic-style short play AI agent, we further expanded high-quality and diverse content supply to capture emerging growth opportunities. Moreover, amid rising marketing budgets from clients across the AI application vertical, we effectively captured the marketing placement spending from AI application clients.

In the fourth quarter of 2025, for online marketing products, we continued to upgrade offerings, including our Universal Auto X (UAX, 全自動投放) placement solutions, AIGC marketing material solutions, livestream digital human solutions, and digital employee solutions. These enhancements reduced barriers to entry for marketing placement, improved clients’ placement experience, and fueled further growth in online marketing spending. Specifically, in the fourth quarter of 2025, the penetration rate of our UAX placement solutions accounted for nearly 80% of the spending from non-e-commerce marketing services, with its penetration among active non-e-commerce marketing clients exceeding 90%.

For e-commerce marketing services, following our consolidation of e-commerce business and related online marketing services in late September 2025 to enhance traffic synergy, we established our closed-loop capabilities covering traffic, transaction, marketing conversion and merchant services. This initiative was designed to align our platform’s overall revenue growth with merchant mix refinement, enabling e-commerce merchant’s GMV per Mille (GPM) and Cost per Mille (CPM) for e-commerce marketing services to improve in tandem in the fourth quarter of 2025. In the first half of 2025, we completed the capability refinement of our omni-platform marketing solution. In the second half of 2025, we focused more on addressing differentiated scenario needs across diverse customer segments, effectively driving incremental GMV generated for e-commerce merchants across omni-domain scenarios and enhancing business stability. In the fourth quarter of 2025, our omni-platform marketing solutions accounted for a greater share of total spending from e-commerce marketing services, rising further to 75%. In addition, our fully managed auto-placement product combo for small-and medium-sized merchants gained broader adoption and recognition, resulting in a significant increase in spending by these customers. In the fourth quarter of 2025, by continuously optimizing our pan-shelf-based e-commerce scenarios, and strengthening the synergy across omni-domain supply and aligned distribution, our e-commerce marketing services revenue in pan-shelf-based scenarios increased rapidly.

E-commerce

In the fourth quarter of 2025, our e-commerce GMV grew 12.9% year-over-year to RMB521.8 billion. Building on our systematic omni-domain operations strategy, we further integrated the pathway between public-domain traffic conversion and private-domain asset accumulation, supporting the merchants’ stable, sustainable operational development across diverse scenarios. During the fourth quarter of 2025, we continued to empower merchants to expand their private domains and improve operational efficiency, broadening the variety of supply. As a result, the repeat-purchase frequency of active e-commerce users further increased year-over-year. Meanwhile, by strengthening the operations of our key product categories and deepening our understanding of core user needs, we drove continued growth in ARPPU in the fourth quarter of 2025.

In the fourth quarter of 2025, we leveraged the combined strengths of service providers, agencies and industrial zones to broaden our e-commerce supply pipeline. During the fourth quarter of 2025, both newly on-boarded merchants and newly on-boarded active merchants grew year-over-year and quarter-over-quarter, driving our active merchant base to another record high, up 7.3% year-over-year. Furthermore, in the fourth quarter of 2025, we launched the Voyage Initiative (乘風計劃), focusing on in-depth partnerships with top-tier brands in diverse sectors. Through systematic resource empowerment, the initiative aimed to explore mutual growth opportunities for both the platform and the brands. At the end of December 2025, we began to gain preliminary benefits from our high-quality product and content supply, along with a more optimized merchant structure.

In the fourth quarter of 2025, in terms of our livestreaming scenario development, the Pop-Up Follower Red Envelopes initiative (天降漲粉紅包), which was launched in the third quarter of 2025 to drive targeted follower growth, delivered meaningful results. By increasing the streaming frequency of streamers with over 10,000 followers, the program drove a 12.7% year-over-year increase in the number of average daily active streamers hosting live sessions with over 10,000 followers, further strengthening the virtuous cycle between follower growth and transaction performance. Through coordinated operations with agencies and leading KOL organizations, we expanded our KOL supply. To further empower KOLs, our KOL Blockbuster Initiative (達人爆品計劃) targeted on high-demand product categories, serves as an officially selected product pool trusted by both merchants and KOLs. It drives greater KOL participation in distribution and the penetration of KOLs within our distribution pool continued to rise, with the number of active KOLs more than doubling year-over-year. Supported by our platform-endorsed product offerings, mid-tier and small-and medium-sized KOLs were able to overcome product selection challenges and, with platform traffic support, achieve meaningful leaps in operational scale.

In the fourth quarter of 2025, our omni-domain operations ecosystem, including pan-shelf-based e-commerce and short videos, continued to demonstrate steady and resilient development. The contribution of pan-shelf-based e-commerce GMV to total e-commerce GMV remained broadly stable quarter-over-quarter. We continued to expand our supply scale, driving sustained year-over-year and quarter-over-quarter increases in average daily active merchants for pan-shelf-based e-commerce. Super Links (超級鏈接), our official channel for platform-recommended products, reinforced its position as a core operational tool for shelf-based supply, achieving rapid growth during the fourth quarter of 2025. The Super Links (超級鏈接) penetration rate in shelf-based e-commerce product cards rose to 19.1%. We also encouraged merchants to expand omni-domain operations. By leveraging our marketing hosting tools, we guided merchants in content-driven scenarios to transition toward shelf-based operations, significantly increasing the penetration rate of active merchants using our marketing hosting tools quarter- over-quarter. During the fourth quarter of 2025, we further advanced our short-video e-commerce content supply, prioritizing refined merchant-centric operations. By continuously leveraging the synergy between short videos and live streaming, we enriched our high-quality content supply and optimized funnel efficiency. These efforts led to significant growth in short video e-commerce GMV, which continued to outpace overall e-commerce GMV growth.

In the fourth quarter of 2025, we deepened AI integration across e-commerce scenarios, empowering merchants to improve operational efficiency and drive their growth. The broader rollout of OneRec, OneSearch and other large model technologies across e-commerce scenarios continued to generate incremental business gains. In addition, powered by an e-commerce knowledge graph and leveraging large models’ world knowledge and reasoning capabilities, we deepened our foundational understanding of products, videos and users. This enabled more precise long-term user-interest modeling, improved recommendation diversity and drove higher revisit and repeat purchases. E-commerce content generation capabilities also advanced during the fourth quarter of 2025. Features such as livestreaming highlights and AI-assisted content creation further strengthened merchants’ cross-scenario operating capabilities. To improve operating efficiency, we launched an AI-powered order analysis feature during the fourth quarter of 2025, enabling merchants to identify abnormal orders more effectively and reduce pre-shipment refund rates.

Live streaming

In the fourth quarter of 2025, live streaming revenue reached RMB9.7 billion. We remained focused on fostering a healthy live streaming ecosystem during the fourth quarter of 2025, orienting toward high-quality, value-driven content, and reinforcing the platform’s community-centric value. For live streaming supply, we continued intensifying professional operations of our core competitive categories, including group live streaming and multi-host live streaming, while strengthening coordinated development across multiple categories. This enriched our live streaming content operations portfolio and drove sustained improvements on the supply side. Our Grand Stage (直播大舞台) further deepened integration between online and offline live streaming scenarios, supporting the incubation of distinctive streamers on our platform while boosting user engagement. On the product front, powered by Kling AI (可靈AI)‘s video generation capabilities, our AI Universe (AI萬象) gift series with customizable special effects delivered further enhanced interactive experiences, dynamic motion rendering and improved visual aesthetics. As of the end of the fourth quarter of 2025, the number of cumulative AI Universe (AI萬象) gift creations exceeded 1 million. In addition, we expanded the application of AI capabilities in our live streaming rooms, empowering streamers with AI Interaction Assistants (AI互動助手) and AI Digital Avatar Solutions (AI數字分身服務) to improve streamers’ service efficiency. In the fourth quarter of 2025, our “live streaming+” strategy broadened the boundaries of the live streaming ecosystem while also unlocking additional commercial value. Through refined operations, our Ideal Housing (理想家) and Kwai Hire (快聘) businesses delivered both quality enhancements and greater operational efficiency. In the fourth quarter of 2025, the average monthly number of Ideal Housing (理想家) paying clients increased by over 40.0% year-over-year.

Overseas

In the fourth quarter of 2025, we remained firmly committed to our high-value growth strategy, supporting a virtuous cycle across our overseas business. Despite complex market dynamics, we achieved steady growth in overseas business. On the traffic front, while improving customer acquisition efficiency and optimizing our user growth structure, we reinforced community mindshare through signature content offerings, further expanding our core user base. Brazil, our key market for overseas development, maintained stable average DAUs and average daily time spent per DAU. For online marketing services, we captured the industry opportunity arising from global brands’ expansion in Brazil, growing our client base across diverse industries. In addition, we upgraded our products and solutions and actively explored new content-driven marketing scenarios, including short plays, to improve client performance visibility and unlock new growth momentum, supporting our clients’ long-term development. Our e-commerce business in Brazil achieved steady year-over-year growth in GMV and order volume in the fourth quarter of 2025. Supported by AIGC-driven improvements in e-commerce content quality and operational efficiency, and aided by more refined logistics cost management, our profitability improved significantly.

Corporate social responsibility

Kuaishou remains firmly committed to its mission of “connecting good faith with technology and creating long-term values”, dedicated to building a warm, inclusive, and accessible digital community for everyone. Anchored by short videos and live streaming, we advance digital technologies to deeply empower social-development scenarios across employment, entrepreneurship and rural revitalization. By leveraging digital technologies, we enabled more individuals to experience greater fulfillment and well-being, thereby contributing to the development of a more vibrant and supportive society.

Our Happy Lecture Hall (幸福大講堂) project provides practical new media skills training for women, seniors, young entrepreneurs, people with disabilities and other groups. By the end of 2025, the program expanded to cover over 50 counties and cities nationwide, helping nearly 2 million people develop “short video + live streaming” digital skills. We also launched the Future Enlightenment Classroom (啟智未來學堂) project, supporting rural education across multiple regions by donating digital classroom facilities, offering AI courses, hosting technology-focused summer camps and other initiatives. These efforts have strengthened teaching infrastructure in rural schools across diverse regions, creating greater opportunities for teachers and students to access digital learning and explore cutting-edge technologies.

Proposed distribution of 2025 Final Dividend 

The Board is pleased to announce that it has recommended the payment of a final dividend of HK$0.69 per Share for the year ended December 31, 2025, amounting to approximately HK$3.0 billion in total. Subject to the approval of Shareholders at the 2026 AGM, the proposed final dividend will be paid on or around Tuesday, July 28, 2026 to Shareholders whose names appear on the register of members of the Company on Tuesday, July 7, 2026. 

This reflects the Company’s unwavering commitment to enhancing shareholders value and sharing the benefits of the Company’s strong cash flow generation. Looking ahead, the Company will continue to consider various shareholder return measures, including share buybacks and dividend distributions, subject to its business development needs, market conditions and other relevant factors. 

Business Outlook

As AI technologies rapidly evolve, we remain dedicated to advancing our AI strategy and reinforcing Kuaishou’s position as a leading AI-empowered content platform. Guided by our “technology-driven, user-centric” philosophy, we will stay closely attuned to user needs while deepening AI integration to enhance operational efficiency for our merchants and marketing clients. Furthermore, the continuous expansion of AI applications throughout our content and commercial ecosystem will fuel high-quality growth within our core businesses, unlocking broader commercialization opportunities and delivering sustained, long-term value for our users, creators, partners, and shareholders.

About Kuaishou

Kuaishou is a leading content community and social platform in China and globally, committed to becoming the most customer-obsessed company in the world. Kuaishou uses its technological backbone, powered by cutting-edge AI technology, to continuously drive innovation and product enhancements that enrich its service offerings and application scenarios, creating exceptional customer value. Through short videos and live streams on Kuaishou’s platform, users can share their lives, discover goods and services they need and showcase their talent. By partnering closely with content creators and businesses, Kuaishou provides technologies, products, and services that cater to diverse user needs across a broad spectrum of entertainment, online marketing services, e-commerce, local services, gaming, and much more.

Forward-Looking Statements

Certain statements included in this press release, other than statements of historical fact, are forward-looking statements. Forward-looking statements generally can be identified by the use of forward-looking terminology such as “may”, “might”, “can”, “could”, “will”, “would”, “anticipate”, “believe”, “continue”, “estimate”, “expect”, “forecast”, “intend”, “plan”, “seek”, or “timetable”. These forward-looking statements, which are subject to risks, uncertainties, and assumptions, may include our business outlook, estimates of financial performance, forecast business plans, growth strategies and projections of anticipated trends in our industry. These forward-looking statements are based on information currently available to the Group and are stated herein on the basis of the outlook at the time of this press release. They are based on certain expectations, assumptions and premises, many of which are subjective or beyond our control. These forward-looking statements may prove to be incorrect and may not be realized in the future. Underlying these forward-looking statements are a large number of risks and uncertainties. In light of the risks and uncertainties, the inclusion of forward-looking statements in this press release should not be regarded as representations by the Board or the Company that the plans and objectives will be achieved, and investors should not place undue reliance on such statements. Except as required by law, we are not obligated, and we undertake no obligation, to release publicly any revisions to these forward-looking statements that might reflect events or circumstances occurring after the date of this press release or those that might reflect the occurrence of unanticipated events.

For investor and media inquiries, please contact

Kuaishou Technology

Investor Relations
Email: ir@kuaishou.com 


CONSOLIDATED INCOME STATEMENT

Unaudited

Audited

Three Months Ended

Year Ended

December 31,

2025

September 30,

2025

December 31,

2024

December 31,

2025

December 31,

2024

RMB’Million

RMB’Million

RMB’Million

RMB’Million

RMB’Million

Revenues

39,568

35,554

35,384

142,776

126,898

Cost of revenues

(17,749)

(16,120)

(16,261)

(64,227)

(57,606)

Gross profit

21,819

19,434

19,123

78,549

69,292

Selling and marketing expenses

(11,409)

(10,420)

(11,317)

(42,229)

(41,105)

Administrative expenses

(930)

(688)

(866)

(3,343)

(2,916)

Research and development expenses

(4,143)

(3,650)

(3,451)

(14,491)

(12,199)

Other income

74

27

187

170

533

Other gains, net

379

596

592

1,981

1,682

Operating profit

5,790

5,299

4,268

20,637

15,287

Finance (expense)/income, net

(31)

(40)

19

(149)

236

Share of (losses)/profits of investments
  accounted for using the equity method

(9)

3

(1)

(16)

(29)

Profit before income tax

5,750

5,262

4,286

20,472

15,494

Income tax expenses

(516)

(773)

(312)

(1,848)

(150)

Profit for the period

5,234

4,489

3,974

18,624

15,344

Attributable to:

— Equity holders of the Company

5,229

4,488

3,969

18,617

15,335

— Non-controlling interests

5

1

5

7

9

5,234

4,489

3,974

18,624

15,344


CONSOLIDATED BALANCE SHEET

Audited

Audited

As of December 31,
2025

As of December 31,

 2024

RMB’Million

RMB’Million

ASSETS

Non-current assets

Property and equipment

22,869

14,831

Right-of-use assets

8,545

8,891

Intangible assets

986

1,059

Investments accounted for using the equity method

149

166

Financial assets at fair value through profit or loss

24,100

24,430

Other financial assets at amortized cost

35

62

Deferred tax assets

5,585

6,604

Long-term time deposits

22,015

19,856

Other non-current assets

2,671

1,105

86,955

77,004

Current assets

Trade receivables

8,127

6,674

Prepayments, other receivables and other current assets

7,028

4,646

Financial assets at fair value through profit or loss

42,324

27,050

Other financial assets at amortized cost

9

233

Short-term time deposits

8,630

11,522

Restricted cash

251

47

Cash and cash equivalents

11,180

12,697

77,549

62,869

Total assets

164,504

139,873


CONSOLIDATED BALANCE SHEET

Audited

Audited

As of December 31,

2025

As of December 31,

 2024

RMB’Million

RMB’Million

EQUITY AND LIABILITIES

Equity attributable to equity holders of the Company

Share capital

–

–

Share premium

265,628

268,733

Treasury shares

(602)

(341)

Other reserves

38,873

35,776

Accumulated losses

(224,341)

(242,164)

79,558

62,004

Non-controlling interests

26

20

Total equity

79,584

62,024

Non-current liabilities

Borrowings

11,098

11,100

Financial liabilities at fair value through profit or loss

30

124

Lease liabilities

5,977

6,765

Deferred tax liabilities

241

13

Other non-current liabilities

39

19

17,385

18,021

Current liabilities

Accounts payables

27,209

27,470

Other payables and accruals

29,160

23,113

Advances from customers

4,848

4,696

Borrowings

1,968

–

Financial liabilities at fair value through profit or loss

–

5

Income tax liabilities

388

873

Lease liabilities

3,962

3,671

67,535

59,828

Total liabilities

84,920

77,849

Total equity and liabilities

164,504

139,873


Financial Information by Segment

Unaudited Three Months Ended

December 31, 2025

September 30, 2025

December 31, 2024

Domestic

Overseas

Unallocated
items

Total

Domestic

Overseas

Unallocated
items

Total

Domestic

Overseas

Unallocated
items

Total

RMB’Million

RMB’Million

RMB’Million

Revenues

38,263

1,305

–

39,568

34,400

1,154

–

35,554

34,089

1,295

–

35,384

Operating profit/(loss)

6,065

(59)

(216)

5,790

5,391

(64)

(28)

5,299

4,361

(236)

143

4,268


Audited Year Ended December 31,

2025

2024

Domestic

Overseas

Unallocated
items

Total

Domestic

Overseas

Unallocated
items

Total

RMB’Million

RMB’Million

Revenues

137,702

5,074

–

142,776

122,202

4,696

–

126,898

Operating profit/(loss)

21,202

(76)

(489)

20,637

16,355

(934)

(134)

15,287


Reconciliation of Non-IFRS Accounting Standards Measures to the Nearest IFRS Accounting
Standards Measures

Unaudited

Unaudited

Three Months Ended

Year Ended

December 31,

September 30,

December 31,

December 31,

December 31,

2025

2025

2024

2025

2024

RMB’Million

RMB’Million

RMB’Million

RMB’Million

RMB’Million

Profit for the period

5,234

4,489

3,974

18,624

15,344

Adjusted for:

Share-based compensation expenses

669

651

636

2,640

2,349

Net fair value changes on

  investments(1)

(440)

(154)

91

(617)

23

Adjusted net profit

5,463

4,986

4,701

20,647

17,716

Adjusted net profit

5,463

4,986

4,701

20,647

17,716

Adjusted for:

Income tax expenses

516

773

312

1,848

150

Depreciation of property and

  equipment

1,205

1,031

1,093

3,903

4,064

Depreciation of right-of-use assets

814

802

756

3,215

2,972

Amortization of intangible assets

8

21

26

77

104

Finance expense/(income), net

31

40

(19)

149

(236)

Adjusted EBITDA

8,037

7,653

6,869

29,839

24,770

Note:

(1)    Net fair value changes on investments represents net fair value (gains)/losses on financial assets at fair value
        through profit or loss of our investments in listed and unlisted entities, net (gains)/losses on deemed disposals
        of investments and impairment provision for investments, which is unrelated to our core business and operating
        performance and subject to market fluctuations, and exclusion of which provides investors with more relevant
        and useful information to evaluate our performance.