Home Blog Page 5821

Cloud Comrade Has Earned the Microsoft Azure Virtual Desktop Advanced Specialization

SINGAPORE – Media OutReach – 9 December 2021 – Cloud Comrade (https://cloudcomrade.com/) today announced it has earned the Microsoft Azure Virtual Desktop (formerly Windows Virtual Desktop) advanced specialization, a validation of a partner’s deep knowledge, extensive experience and expertise in deploying, scaling and securing virtual desktop infrastructure on Azure.

Only partners that meet stringent criteria around customer success and staff skilling, as well as pass a third-party audit of their Azure Virtual Desktop technical practices, are able to earn the Microsoft Azure Virtual Desktop advanced specialization.

Supporting secure remote work for employees is more critical than ever. Microsoft Azure Virtual Desktop is a Microsoft solution that seamlessly integrates with other Microsoft products and allows customers to implement virtual desktops in a scalable, secure, and cost-effective way.

Partners with validated capabilities in implementing Azure Virtual Desktop can help customers deploy and navigate the licensing efficiencies it offers to deliver the solution that is most efficient for their organization.


“Distributed workplaces and hybrid/remote work are increasingly becoming the norm rather than the exception. Adapting quickly and seamlessly to this altered environment without compromising on productivity, efficiency, scalability, and security can be challenging for most businesses. The choice of the technology platform/ solution as well as a competent, qualified, and experienced partner are both critical to help a business achieve these objectives. That is why we are excited to earn the Microsoft Azure Virtual Desktop advanced specialization, a reflection of our competence in this area,” said Andy Waroma, Co-Founder & Co-Managing Director, Cloud Comrade.


“As a Microsoft Partner with a Gold Cloud Platform competency, we are confident of our best-in-class capabilities for deploying a range of Microsoft business solutions. We value the collaboration, working relationship and support from Microsoft, which help us maximise the value our clients can get from their deployments of Microsoft products, solutions and technologies.”


Rodney Clark, Corporate Vice President, Global Partner Solutions, Channel Sales and Channel Chief at Microsoft added, “The Microsoft Azure Virtual Desktop advanced specialization highlights the partners who can be viewed as most capable when it comes to deploying Azure Virtual Desktop in Azure. Cloud Comrade clearly demonstrated that they have both the skills and the experience to offer clients a path to transition to desktop-as-a-service in a scalable, secure, and cost-effective way.”


Cloud Comrade offers comprehensive cloud services including strategic consulting, deployment or migration and managed services for companies in a wide range of industries. Besides Microsoft Azure Virtual Desktop, Cloud Comrade’s areas of expertise in Microsoft products and solutions include Office 365, Windows and SAP on Microsoft Azure. For more details, visit: https://appsource.microsoft.com/en-sg/marketplace/partner-dir/e9011111-82f5-4b5e-9f78-62b09cf4eef4/overview

About Cloud Comrade

Cloud Comrade (https://cloudcomrade.com) is a Singapore-based cloud computing consultancy company with a regional footprint in Indonesia and Malaysia. The company offers a comprehensive range of services from strategy and design to deployment, migration, and management of customers’ IT infrastructure. Cloud Comrade partners with the best solution providers in the field of cloud computing and is a preferred Amazon Web Services (AWS) consulting partner in ASEAN, as well as a managed service provider for AWS, Google, and Alibaba Cloud. In January 2019, ST Telemedia (sttelemedia.com), an active strategic investor specializing in communications & media, data centers, and infrastructure technology businesses, acquired a majority stake in the company. For more information on Cloud Comrade, visit cloudcomrade.com

#CloudComrade

Kobe Global Technologies’ Research Reveals Millennials And Gen Z Value Authenticity On Social Media

SINGAPORE – Media OutReach – 9 December 2021 – Research conducted by Kobe Global Technologies in an effort to study Gen Z’s and Millennials’ spending habits in relation to social media advertising has revealed that Millennials and Gen Z look towards authenticity and unfiltered content curation from content creators and social media influencers. This means raw and authentic content is more likely to convince these two demographics to engage with the brand.

In this day and age, Millennials and Gen Z are not only tech-savvy, but they are also more mindful of what they digest online and how marketing advertisements or contents are packaged and communicated to them. These two demographics are no longer viewing celebrity endorsements for products or services alone; they are looking for internet personalities who embody their values and social beliefs, as well as someone who openly embraces their natural flaws or mistakes that a layperson can resonate with.


This research has been backed up by the two campaigns that Kobe has assisted its clients with. By entrusting the social influencers, who understand what content style works best for their followers, to produce authentic content that speaks to consumers, Kobe’s clients – Genki Sushi and Livinguard – were able to reap the benefits. The followers were able to sense the influencers’ honesty, and therefore, they were more receptive to what these key opinion leaders had to say.


Moreover, understanding that consumers disliked being told what to do, the influencers avoided including a call to action in the initial phases of the Livinguard campaign, thereby generating intrigue among followers. On the day of the launch, the content creators were flooded with queries on how to purchase the products.


Through the brilliant execution of these said campaigns, Genki Sushi saw a 64% increase in the sales of its Xmas Deluxe Dai Man Zoku Set from the company’s previous year, and Livinguard saw sales spike by more than 300% on the day of its Instagram campaign, easily cementing this launch as the company’s highest sales count since its inception in Singapore.


And Genki Sushi was clearly happy with the results, as the company has continued its partnership with Kobe for its various marketing campaigns since January 2020. The acknowledgment of Kobe’s good work is also echoed by Mr. Gavin Gan, Executive Director of Hoe Hin Pak Fah Yeow Mfy. Ltd, another beneficiary of Kobe’s authentic approach to content creation. When requested to provide feedback, Mr. Gan had this to say, “Kobe Global Technologies provides good professional service and insightful knowledge on social media and influencer marketing.”


With online viewers and consumers being at the heart of social media marketing, getting the right people to spread the right message to the right audience is essential. And Kobe’s research has made the company aware of this fact, leading to a transformation in the way the organization approaches influencer marketing.

About Kobe Global Technologies

Kobe Global Technologies is a pioneering company in Singapore delivering consumer-first social media marketing campaigns. With access to over 20,000 content creators across Southeast Asia and its patented A.I. technology that combs through millions of data points, the company is able to deliver influence for more than 500 brands globally. For more information on the company’s services, please visit https://www.getkobe.com/

#KobeGlobalTechnologies

HelperPlace New Survey Reveals the Loosen Travel Restrictions is Not Enough to Cover the Demand of Domestic Helper

  • The looser travel restrictions for the domestic helper is not enough to cover the high demand of local families; given the current difficulty and cost to hire overseas helpers, local helpers are constantly in shortage
  • Despite frozen minimum wage, 9.60% annual average increase in domestic helper monthly salary, so employers need to offer a higher salary to easier find a helper
  • Domestic helpers working conditions need concern, especially under pandemic

HONG KONG SAR – Media OutReach – 9 December 2021 – For the 3rd consecutive year, HelperPlace has been surveying the average monthly salary of foreign domestic helpers working in Hong Kong. This year, HelperPlace conducted an online survey among domestic helpers in Hong Kong from January 2021 to December 2021 and received over 12,501 responses. One of the objectives is to measure the impact of the pandemic on the job market. The results provide insights into the actual average salary, factors affecting salary, expectations, and working conditions of helpers in 2021.

The Significant Impact of the Increase in Salary in 2021


HelperPlace’s annual salary survey has been conducted three years in a row. In 2021, the average actual monthly salary for a foreign domestic helper is HK$5,288. The average monthly salary for 2019 and 2020 are $4,765 and $4,825, respectively. It reveals a significant annual increase of 9.60% from 2020 to 2021 compared to only 1.26% from 2019 to 2020. Since 2019 September, the minimum monthly salary has been frozen at HK$4,630 by the government.

In the context of the travel restrictions, the shortage of overseas helpers has brought up the market salary. Even though the government has loosened up the restrictions, the population of overseas workers has decreased by over 20,000 in less than a year. The struggle to book quarantine rooms for helpers due to its limited number, the long process, and the extra cost of HK$15,000 (fees for quarantine hotel and food) to hire an overseas helper push employers to find other solutions. As a result, employers have a preference for hiring foreign domestic helpers who are already settled in Hong Kong. Therefore this phenomenon creates a large demand for a limited pool of workers. The results show that the impact of the COVID on domestic helper salary has been fully reflected in 2021.

Territorial Difference of Salary


The survey shows the territorial difference in average salary among domestic helpers. The Hong Kong Island has the highest average salary with HK$5,612, followed by Kowloon of HK$5,148, and the least in New Territories with HK$5,093.


Factors of Domestic Helper Salary


Besides salary, the survey also conducted interviews on the working hours, no. of kid, and the years of helpers’ experience. The average salary increases with the number of years of experience of helpers. However, the results show a shocking negative relationship between workload in relation to salary. The higher the working hour and the number of kids in the employer’s family, the lower the salary. It reflects that domestic helper salary is not reflecting their workload.

Based on the survey, the hiring channel is one of the important factors for salary. The average salary ranks lowest for the agency ($4,683), then online platform ($5,393), and highest for employer referral with $5,418. This can be explained by the fact that direct hiring through online platforms and employer referral can save a considerable amount of agency fees, create more trust, and result in higher monthly salaries.


The working hour and working conditions still need improvement


The survey also reflects on the long working hours issue and poor working conditions of some domestic helpers in Hong Kong. For instance, nearly 61% of respondents work over 12 hours a day.


According to Hong Kong law, employers are obligated to provide food allowance or free food to domestic helpers. 81% of the survey respondents said their employers provide free food, and 12% out of them said that they do not have enough food provided by employers.


For the living conditions, most respondents either have their separate room (56%) or share a room with kids (20%), elderlies (2%), or other workers (10%). However, around 11% of respondents stay in the living room, bathroom, or kitchen of the employer’s house. About 1% of respondents are live-out, although the law forbids it.


Despite the poor working and living conditions for some domestic helpers, over 70% of respondents find the relationship with the employer at least acceptable or better.


Forecast for next year


There is no doubt that the travel restriction will persist for a few more months. This may result in a more severe shortage of local helpers, assuming the same domestic helper quotas for entering Hong Kong. In the last 3 months, it was not rare to see workers asking for more than HK$7,000 per month.


Conclusion


Despite the higher bargaining power for a better salary, the local helpers who have finished their 2-year contracts are also looking for better working conditions, such as separate rooms, lower workloads, and locations in Hong Kong Island to conveniently hang out with friends on weekends. It is undeniable that employers who have better offers can attract domestic helpers to start or continue working for them. It will create more difficulties for the middle class and lower-income families.

About HelperPlace

HelperPlace is an ethical platform for foreign domestic workers founded in Hong Kong in 2016. With the largest domestic helper community of 170,000+ members and collaborating with NGOs or international organizations, it was recognized as creating a fair impact on this community. Its website and mobile app allow helpers to connect freely with potential employers, providing an alternative to the traditional employment agency.

#HelperPlace

The issuer is solely responsible for the content of this announcement.

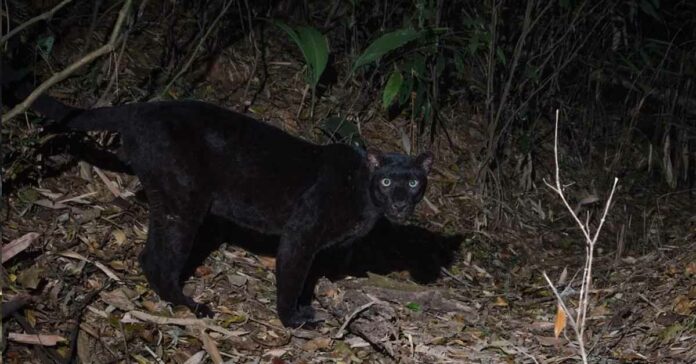
Thai Construction Tycoon Handed Prison Sentence for Butchering Black Leopard

Rare black indochinese leopard
Rare black Indochinese leopard.


A Thai construction Tycoon who shot and cooked a rare black leopard at a wildlife sanctuary in 2018 has been handed a three-year jail sentence by the Supreme Court of Thailand.

Meta Bans Myanmar Military Businesses on its Platforms

Meta Platforms Inc


Meta Platforms Inc, formerly Facebook, said in a statement on Wednesday that it would ban all Myanmar military-controlled businesses from its platforms.

Asia Pacific Economy Forecast to Return to World-Leading Growth in 2022, Maintaining into 2023

  • The Asia Pacific office market remained resilient, being the only region to record consecutive quarters of positive net absorption since the pandemic
  • Mainland China Tier 1 markets experienced record office demand in 2021
  • Total regional investment volume in 2022 is expected to be on par with the recent 2019 peak at around $180bn
  • Long-term opportunities for retail assets remain for China, India, SE Asia


HONG KONG SAR – Media OutReach – 8 December 2021 – The Asia Pacific economy is set to rebound in 2022 and regain top position in the second half of the year with an expected 4.5% real average annual GDP, while growth in the other two major regions normalizes, according to Cushman & Wakefield’s latest report titled Catch ’22 – Asia Pacific Commercial Real Estate Outlook 2022.


“India is forecast to lead regional growth in 2022, averaging over 9% for the year, in large part due to restrictions being lifted and a resultant leap in domestic consumption and production,” said Dr. Dominic Brown, Head of Insight & Analysis, Asia Pacific at Cushman & Wakefield. “Similarly, Singapore, Japan and South Korea are all forecast to experience above average growth in 2022 driven by strong demand for exports. We are also expecting rebound growth in Australia.”

Growth in mainland China in 2022 will normalize somewhat following a particularly strong 2021. Hong Kong SAR is forecast to perform closer to average economic growth rates of the 5-years prior to the pandemic.


Although unemployment remains elevated across the region, levels in most markets are well below their respective pandemic peaks and forecast to sit at or below their respective five-year average over the year ahead. However, aggregate figures of unemployment hide finer details – the “K-shaped” recovery path revealed weakness in retail, tourism and service-oriented sectors compared to tight labour conditions in professional services, IT, finance and manufacturing. Furthermore, countries that are reliant on immigration to boost labour pools, such as Singapore and Australia, are more exposed to labour shortages at least until global migration flows regain momentum. As such, there is an increasing mismatch between required business skills and available labour force which has intensified the war for talent.


There is also mounting evidence that the current trend of more workers actively considering changing jobs within the next 12 months — the so-called “Great Resignation” — may arrive in parts of Asia Pacific. Fundamentally the key message is that corporate occupiers should prioritise talent retention and attraction in the immediate term as well as enhancing productivity through investment in technology and real estate.


Office market outlook: Upbeat as region shows resilience through the pandemic

According to the Catch ’22 report, the Asia Pacific office market has shown remarkable resilience, being the only region to record consecutive quarters of positive net absorption since the onset of the pandemic. Although regional vacancy has edged upwards, it is only marginal and primarily driven by supply exceeding demand, which in turn has exerted only a modest downward pressure on rents.


The outlook for the region is similarly upbeat, with office demand for the full year in 2021 expected to reach 55 million square feet (msf). This is 77% above 2020 levels despite much of the region re-entering prolonged lockdowns as the Delta variant emerged, and this is also in no small part due to record demand in Tier 1 markets in mainland China.


Looking to 2022, demand is expected to increase further to 72 msf – reflective of a stronger recovery across the entire region – before returning to pre-pandemic levels of around 83msf in 2023. Although flexible working practices are likely to be more widely adopted across the region, their impact on demand is expected to be minimal as more employees are already returning to office reflecting the than in the U.S. and Europe. This is especially the case in China, where employees’ desire to work frequently from outside of the office is markedly lower.


Looking ahead, projected employment growth and a gradual return to office-based working is likely to offset the underlying headwind from remote working. Although the regional vacancy level is forecast to increase to 18% in 2023, this disguises the fact that many markets across the region are entering a period of restrained supply over the next two years.


Shaun Brodie, Head of Occupier Research, Greater China, Cushman & Wakefield, said: “Office demand is expected to pick up across most markets in 2022, as occupiers increasingly make decisions around their corporate footprints, although mainland China is likely to moderate somewhat following the record demand levels seen in 2021. On the supply side, many markets are forecast to receive below average amounts of new supply. New supply in mainland China Tier 1 cities is currently around 20% below average.

Keith Chan, Head of Research, Hong Kong, Cushman & Wakefield, said: “In contrast to the undersupply position in mainland China, Hong Kong is set to welcome robust levels of new supply in the coming two years. With almost 5 msf of new completions coming to the market, we expect the city’s rental levels to remain competitive for the next 12 to 24 months. This actually provides a window of opportunity for occupiers to secure premium space at affordable prices, and for landlords to revisit their tenant profiles for sustainable growth.”

Consequently, rents across most of the region’s markets are now forecast to reach a trough in late 2021 through to early 2022, approximately 12 months earlier than envisaged at the start of this year.


Investment outlook: On track to set another new record in 2021

Although the investment market has not been immune to the negative impacts of the pandemic, it has also been comparatively quick to rebound. Investment volumes in 2022 are forecast to match record levels seen in 2019 at around USD180bn. Key drivers include: still ultra-low interest rates despite modest increases in the past year, real estate as an inflation hedge, record amount of dry-powder and an intensified focus on capital deployment by investors.  


While we expect the investment market to remain highly active, a greater focus on industrial assets may dampen average deal size, hence greater transaction activity may not result in higher overall volume. On the upside, total volume may exceed the USD180bn forecast should sufficient high-quality assets or large portfolios be brought to market.


Catherine Chen, Head of Capital Markets Research, Greater China, Cushman & Wakefield, said: “Emerging asset classes such as data centers, multifamily and life sciences have also gained traction among investors seeking higher yields and/or lower volatility. All have strong growth outlook prospects and offer good diversification benefits. These asset classes are expected to be increasingly sought-after by the investor community, with the multifamily sector starting to gain traction in certain cities in mainland China.”


Finally, despite the undoubted impact of the pandemic, the retail and leisure/tourism sectors show few signs of distress. Non-discretionary retail constantly proves itself largely recession-proof. The strength of rebound in domestic consumption and tourism flows will determine the outlook for discretionary expenditure. However, several markets across the region, specifically mainland China, India and South East Asia, remain under-served by physical retail space and so longer-term opportunities in these markets should not be ignored.

Click here to download Catch ’22: Asia Pacific Commercial Real Estate Outlook 2021-22.


About Cushman & Wakefield

Cushman & Wakefield (NYSE: CWK) is a leading global real estate services firm that delivers exceptional value for real estate occupiers and owners. Cushman & Wakefield is among the largest real estate services firms with approximately 53,000 employees in 400 offices and 60 countries. Across Greater China, 22 offices are servicing the local market. The company won four of the top awards in the Euromoney Survey 2017, 2018 and 2020 in the categories of Overall, Agency Letting/Sales, Valuation and Research in China. In 2019, the firm had revenue of $ 8.8 billion across core services of property, facilities and project management, leasing, capital markets, valuation and other services. To learn more, visit www.cushmanwakefield.com or follow @CushWake on Twitter.

#Cushman&Wakefield

Cushman & Wakefield: Asia Pacific Economy Forecast to Return to World-Leading Growth in 2022, Maintaining into 2023

  • The Asia Pacific office market remained resilient, being the only region to record consecutive quarters of positive net absorption since the pandemic
  • Mainland China Tier 1 markets experienced record office demand in 2021
  • Total regional investment volume in 2022 is expected to be on par with the recent 2019 peak at around $180bn
  • Long-term opportunities for retail assets remain for China, India, SE Asia


HONG KONG SAR – Media OutReach – 8 December 2021 – The Asia Pacific economy is set to rebound in 2022 and regain top position in the second half of the year with an expected 4.5% real average annual GDP, while growth in the other two major regions normalizes, according to Cushman & Wakefield’s latest report titled Catch ’22 – Asia Pacific Commercial Real Estate Outlook 2022.


“India is forecast to lead regional growth in 2022, averaging over 9% for the year, in large part due to restrictions being lifted and a resultant leap in domestic consumption and production,” said Dr. Dominic Brown, Head of Insight & Analysis, Asia Pacific at Cushman & Wakefield. “Similarly, Singapore, Japan and South Korea are all forecast to experience above average growth in 2022 driven by strong demand for exports. We are also expecting rebound growth in Australia.”

Growth in mainland China in 2022 will normalize somewhat following a particularly strong 2021. Hong Kong SAR is forecast to perform closer to average economic growth rates of the 5-years prior to the pandemic.


Although unemployment remains elevated across the region, levels in most markets are well below their respective pandemic peaks and forecast to sit at or below their respective five-year average over the year ahead. However, aggregate figures of unemployment hide finer details – the “K-shaped” recovery path revealed weakness in retail, tourism and service-oriented sectors compared to tight labour conditions in professional services, IT, finance and manufacturing. Furthermore, countries that are reliant on immigration to boost labour pools, such as Singapore and Australia, are more exposed to labour shortages at least until global migration flows regain momentum. As such, there is an increasing mismatch between required business skills and available labour force which has intensified the war for talent.


There is also mounting evidence that the current trend of more workers actively considering changing jobs within the next 12 months — the so-called “Great Resignation” — may arrive in parts of Asia Pacific. Fundamentally the key message is that corporate occupiers should prioritise talent retention and attraction in the immediate term as well as enhancing productivity through investment in technology and real estate.


Office market outlook: Upbeat as region shows resilience through the pandemic

According to the Catch ’22 report, the Asia Pacific office market has shown remarkable resilience, being the only region to record consecutive quarters of positive net absorption since the onset of the pandemic. Although regional vacancy has edged upwards, it is only marginal and primarily driven by supply exceeding demand, which in turn has exerted only a modest downward pressure on rents.


The outlook for the region is similarly upbeat, with office demand for the full year in 2021 expected to reach 55 million square feet (msf). This is 77% above 2020 levels despite much of the region re-entering prolonged lockdowns as the Delta variant emerged, and this is also in no small part due to record demand in Tier 1 markets in mainland China.


Looking to 2022, demand is expected to increase further to 72 msf – reflective of a stronger recovery across the entire region – before returning to pre-pandemic levels of around 83msf in 2023. Although flexible working practices are likely to be more widely adopted across the region, their impact on demand is expected to be minimal as more employees are already returning to office reflecting the than in the U.S. and Europe. This is especially the case in China, where employees’ desire to work frequently from outside of the office is markedly lower.


Looking ahead, projected employment growth and a gradual return to office-based working is likely to offset the underlying headwind from remote working. Although the regional vacancy level is forecast to increase to 18% in 2023, this disguises the fact that many markets across the region are entering a period of restrained supply over the next two years.


Shaun Brodie, Head of Occupier Research, Greater China, Cushman & Wakefield, said: “Office demand is expected to pick up across most markets in 2022, as occupiers increasingly make decisions around their corporate footprints, although mainland China is likely to moderate somewhat following the record demand levels seen in 2021. On the supply side, many markets are forecast to receive below average amounts of new supply. New supply in mainland China Tier 1 cities is currently around 20% below average.

Keith Chan, Head of Research, Hong Kong, Cushman & Wakefield, said: “In contrast to the undersupply position in mainland China, Hong Kong is set to welcome robust levels of new supply in the coming two years. With almost 5 msf of new completions coming to the market, we expect the city’s rental levels to remain competitive for the next 12 to 24 months. This actually provides a window of opportunity for occupiers to secure premium space at affordable prices, and for landlords to revisit their tenant profiles for sustainable growth.”

Consequently, rents across most of the region’s markets are now forecast to reach a trough in late 2021 through to early 2022, approximately 12 months earlier than envisaged at the start of this year.


Investment outlook: On track to set another new record in 2021

Although the investment market has not been immune to the negative impacts of the pandemic, it has also been comparatively quick to rebound. Investment volumes in 2022 are forecast to match record levels seen in 2019 at around USD180bn. Key drivers include: still ultra-low interest rates despite modest increases in the past year, real estate as an inflation hedge, record amount of dry-powder and an intensified focus on capital deployment by investors.  


While we expect the investment market to remain highly active, a greater focus on industrial assets may dampen average deal size, hence greater transaction activity may not result in higher overall volume. On the upside, total volume may exceed the USD180bn forecast should sufficient high-quality assets or large portfolios be brought to market.


Catherine Chen, Head of Capital Markets Research, Greater China, Cushman & Wakefield, said: “Emerging asset classes such as data centers, multifamily and life sciences have also gained traction among investors seeking higher yields and/or lower volatility. All have strong growth outlook prospects and offer good diversification benefits. These asset classes are expected to be increasingly sought-after by the investor community, with the multifamily sector starting to gain traction in certain cities in mainland China.”


Finally, despite the undoubted impact of the pandemic, the retail and leisure/tourism sectors show few signs of distress. Non-discretionary retail constantly proves itself largely recession-proof. The strength of rebound in domestic consumption and tourism flows will determine the outlook for discretionary expenditure. However, several markets across the region, specifically mainland China, India and South East Asia, remain under-served by physical retail space and so longer-term opportunities in these markets should not be ignored.

Click here to download Catch ’22: Asia Pacific Commercial Real Estate Outlook 2021-22.


About Cushman & Wakefield

Cushman & Wakefield (NYSE: CWK) is a leading global real estate services firm that delivers exceptional value for real estate occupiers and owners. Cushman & Wakefield is among the largest real estate services firms with approximately 53,000 employees in 400 offices and 60 countries. Across Greater China, 22 offices are servicing the local market. The company won four of the top awards in the Euromoney Survey 2017, 2018 and 2020 in the categories of Overall, Agency Letting/Sales, Valuation and Research in China. In 2019, the firm had revenue of $ 8.8 billion across core services of property, facilities and project management, leasing, capital markets, valuation and other services. To learn more, visit www.cushmanwakefield.com or follow @CushWake on Twitter.

#Cushman&Wakefield

Insolvency petition against real estate conglomerate ready – International creditor and DMSA seek co-venturers filing for insolvency too

BERLIN, GERMANY – Newsaktuell – 8 December 2021 – The Chinese real estate developer China Evergrande Group once again defaulted on overdue interest payments on December 6, 2021. The previous Friday, the company officially admitted for the first time that it was in the very deepest financial trouble. The debts of the real estate giant now amount to more than $300 billion. In cooperation with DMSA Deutsche MarktScreening Agentur GmbH, a creditor has prepared an insolvency petition against Evergrande Holding. Now, fellow campaigners are being sought before the application is filed with the court.


A bondholder of China Evergrande Group, Liechtenstein-based Financial Market Partners Capital (FMPC) Consulting AG, has been preparing an insolvency petition against the Cayman Islands-registered Evergrande Holding since November 22. FMPC Consulting AG was supported and advised by DMSA Deutsche MarktScreening Agentur GmbH, among others.

(Note for the editorial offices: More about FMPC Capital AG and its investment in Evergrande bonds can be found at the end of this press release).


In the meantime, the application has been completed and can be filed at any time with the Grand Court of the Cayman Islands in George Town. As FMPC Consulting AG sees itself as the administrator of all international Evergrande creditors and in order to reduce the cost risk for each applicant, the company offers other international creditors to join its proceedings.


On Tuesday, Dec. 7, Bloomberg news agency reported two holders of U.S. dollar bonds issued by Evergrande subsidiary Scenery Journey said they had not received interest payments by the end of the 30-day grace period. A total of $82.5 million in interest would have been due no later than Dec. 6.


Previously, in the case of non-performing bonds issued by the Evergrande conglomerate, there had been repeated reports in international media that interest payments had been made at the last second after all. “However, these reports were not confirmed to us either by Evergrande itself or by the paying agents of the bonds,” explains Dr. Marco Metzler, Chairman of the Board of Directors of FMPC Consulting AG and Senior Analyst at DMSA Deutsche MarktScreening Agentur GmbH. “In this respect, the current Bloomberg reports represent a further aggravation of the situation,” Dr. Metzler continued.

An aggravation with announcement: Already on Friday, December 3, Evergrande had officially admitted for the first time in a statement to the Hong Kong Stock Exchange – the home stock exchange of the holding company – that there was “no guarantee that the group will have sufficient funds to continue to meet its financial obligations”.


“This official statement alone has confirmed our assessment of the Group’s absolutely desolate financial situation,” explains Dr. Marco Metzler, Chairman of the Board of Directors of FMPC Consulting AG and Senior Analyst at DMSA Deutsche MarktScreening Agentur GmbH. He finds the default on interest payments hardly surprising for another reason: “We have still not received overdue interest for our bonds – which should have been paid by November 10 at the latest. And this despite the fact that it has been widely reported in the press that the overdue interest payments to international investors have been made.” In Dr. Metzler’s view, the official statement on December 3 and the final default on interest payments on December 6 for the Evergrande subsidiary’s bond represent two events of default at once for all 23 outstanding international bonds of the Evergrande conglomerate with a nominal value of $23.7 billion. “Almost all of it will be lost,” fears Dr. Metzler.


Michael Ewy, Managing Director of DMSA Deutsche MarktScreening Agentur GmbH, adds, “With the insolvency application we helped prepare, we are now trying to save what can be saved for FMPC Consulting AG and other international creditors.” The fear of financial analyst Metzler: “Evergrande is insolvent, but officially not yet insolvent. With the default on a bond now confirmed in the press for the first time, the management of the Evergrande holding company must file for insolvency if it does not want to be guilty of dragging its feet. However, since this application has not yet been made, we – the DMSA and FMPC Consulting – are concerned that assets may be removed from the insolvency estate.”


“In view of all these developments, it was right to start preparing an insolvency petition against Evergrande already at the end of November “, explains Dr. Marco Metzler in his capacity as Chairman of the Board of Directors of FMPC Consulting AG. He invites affected international investors to join the application. The application is to be filed with the competent court in George Town within the next few days.

Upon acceptance of the insolvency petition, an insolvency administrator will begin winding up the Evergrande Group and liquidating the assets for investors and creditors. “The prices of all Evergrande securities – stocks and bonds alike – will fall to virtually zero in the process,” predicts senior analyst Metzler. “But all distressed sales beginning with the filing date can then also be reversed.”


However, DMSA senior analyst Metzler believes there is little hope for Evergrande’s turnaround. “The restructuring analysis by Fitch Ratings – my former employer and one of the three largest rating agencies in the world – assumes that Evergrande would be liquidated at a restructuring rate of zero to ten percent.” That means creditors would get back a maximum of one-tenth of the capital they invested, if access to assets in China is even possible.

“The fact that the Chinese government has now sent high-ranking state officials to Evergrande’s boardroom and thus de facto controls the group does not necessarily mean that all claims – especially those of foreign investors – will also be serviced,” fears Dr. Metzler. Rather, he sees it as likely that Evergrande’s inevitable insolvency will lead to a host of other bankruptcies. “To avoid internal unrest, China would then be forced to return to a hard-line communist approach,” concludes Dr. Metzler. In his view, this would ultimately imply that all of China’s international debt of around $585 billion would no longer be serviced, and equity investments by foreign investors of around $600 billion would also have to be written off completely – with devastating consequences for the global banking system and the entire world economy.


“Supply chains would be even more strained than they already are today. This, in turn, would then inevitably lead to galloping inflation in the U.S., Europe and other countries. As a result, there would be extreme distortions in the global financial system – with insolvencies of players who are still considered rock solid today,” fears Dr. Metzler. “Triggered by a Chinese financial virus called Evergrande, the world could face a ‘Great Reset,’ the final collapse of the current global financial system.”

About Financial Market Partners Capital (FMPC) Consulting AG:

Financial Market Partners Capital (FMPC) Consulting AG, is a private investment and advisory firm based in Ruggell, Liechtenstein. As a single family office, FMPC Consulting AG invests exclusively own funds of its owner, the Metzler family.


About the Evergrande investment of FMPC Consulting AG:

FMPC Consulting AG holds 200 units of the EVERRE 10 1⁄2, 11 April 2024 bond (ISIN: XS19 8204 0641) with a nominal value of 200,000 US dollars. These were purchased on November 01, 2021 for 50,000 US dollars via the house bank of FMPC Consulting AG and have since been held in custody at SIX Switzerland via the house bank in Liechtenstein. Already on October 11, 2021 an interest payment for this bond was missed. The bond terms and conditions provide for this case: If the payment of the accrued interest is not made on the actual payment date, but still during the 30-day grace period, this interest payment is to be credited to the seller of the bond. If, on the other hand, payment of the accrued interest is made after the grace period (grace period), it is credited to the purchaser upon payment. This means that if payment is made after the grace period – in this case, after November 10, 2021 – this payment must be made to FMPC Consulting AG for the securities held by FMPC Consulting AG. Contrary to the widespread reporting of alleged interest payments, this has not happened to date.

FMPC Consulting AG therefore requested an official statement on the interest payments from Clearstream and Citibank as paying agents for the bond more than a week ago. This official statement has not been received by FMPC Consulting AG to date.

About the Evergrande proceedings in China:

Proceedings against China Evergrande Group are also currently underway in China. For example, at the Wuhan Huangpi District People’s Court, the Harbin Daoli District People’s Court, the Jilin Gong District People’s Court as well as other Chinese courts. The cases have all been accepted by the courts but have not yet been decided.

For example, between October 8, 2021 and November 16, 2021, Shanghai Quanzhu Holdings Group Co. filed hundreds of lawsuits totaling 237.92 million yuan (US$37.28 million) against Evergrande in courts in China. The lawsuits relate to several completed construction contracts with Evergrande Real Estate Group Limited as well as its affiliated subsidiaries. Shanghai Quanzhu is using this route to claim priority payment for construction work. In total, Chinese courts have so far accepted at least 333 lawsuits filed by Shanghai Quanzhu for decision.

About DMSA Deutsche Markt Screening Agentur GmbH:

The research house, which has the same owner as FMPC Consulting AG, the Metzler family, sees itself as an advocate for consumers, private customers and private investors. For them, DMSA bundles important and decision-relevant information and prepares it in an easily understandable way. DMSA works with FMPC Consulting AG as needed.

The issuer is solely responsible for the content of this announcement.